
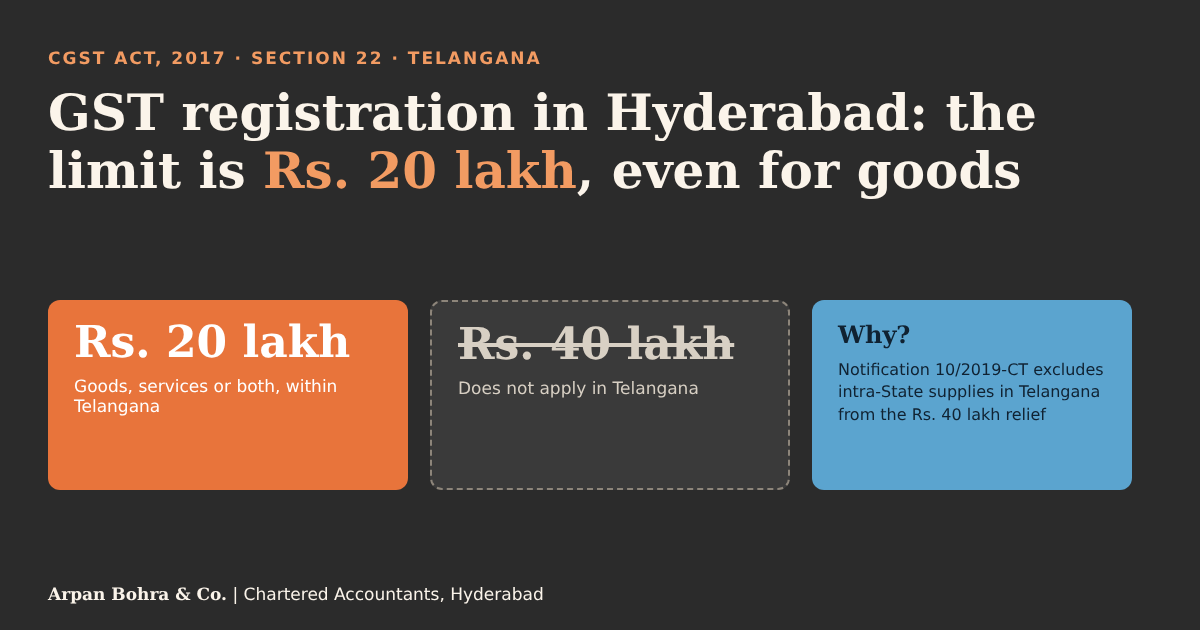
A trader in Kukatpally sells only goods, only within Telangana, and earns Rs. 25 lakh a year. In many States, no registration would be needed. In Telangana, registration is required.
Short answer: in Telangana the GST registration limit is Rs. 20 lakh of aggregate turnover for goods, services or both. The higher Rs. 40 lakh limit for suppliers of goods does not apply here, because Notification No. 10/2019-Central Tax expressly excludes Telangana.
Why Telangana’s GST registration limit is Rs. 20 lakh
Section 22(1) of the CGST Act, 2017 requires registration once aggregate turnover in a financial year exceeds Rs. 20 lakh (Rs. 10 lakh in special category States). Notification No. 10/2019-Central Tax, effective 1 April 2019, raised this to Rs. 40 lakh for persons supplying only goods, but it does not cover intra-State supplies made in a list of States and Union territories that includes Telangana. Thresholds can change by notification, so confirm the current position before relying on it.
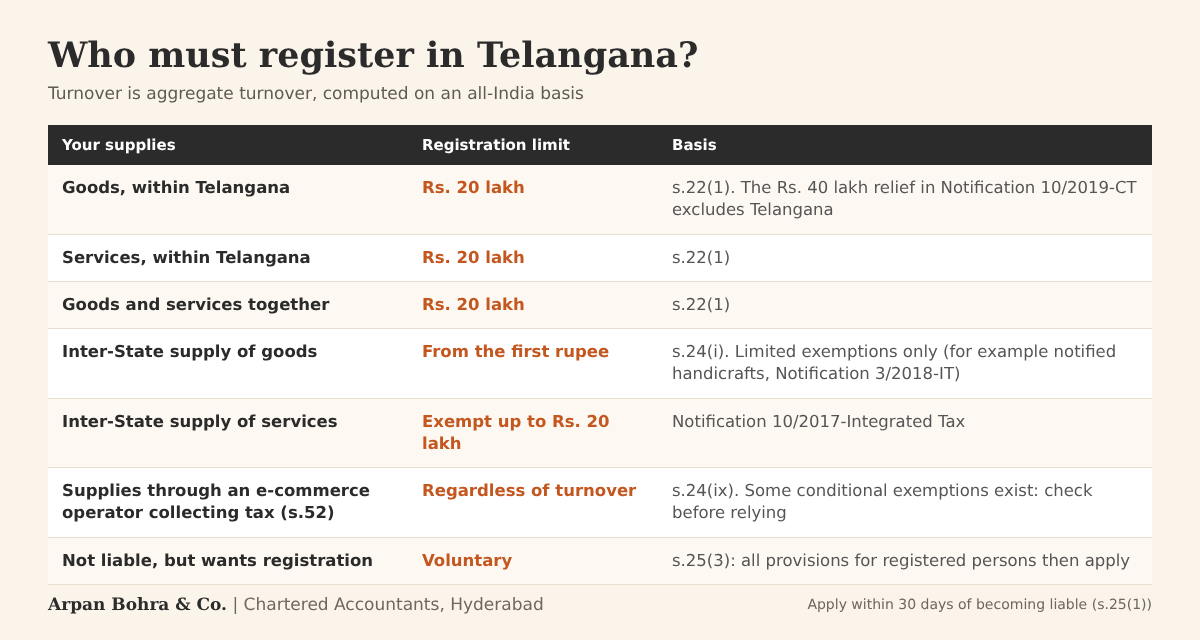
Who must register in Hyderabad?
What counts as aggregate turnover
Under section 2(6), aggregate turnover is the combined value of taxable supplies, exempt supplies, exports and inter-State supplies of all businesses under the same PAN, computed on an all-India basis. It excludes GST and cess, and excludes inward supplies on which you pay tax under reverse charge. A Hyderabad business with a branch in another State therefore adds both together.
Registration is compulsory from the first rupee in these cases
Section 24 overrides the turnover limit for, among others, casual taxable persons, non-resident taxable persons, persons liable under reverse charge (subject to notified exemptions), e-commerce operators and persons supplying through them (subject to notified exemptions), and persons supplying goods inter-State. Inter-State supply of services is exempt from registration up to Rs. 20 lakh under Notification No. 10/2017-Integrated Tax.
Deadline and voluntary registration
Under section 25(1), apply within 30 days of becoming liable. Counting turnover against the limit should be done month by month, not at year end. A business below the limit may register voluntarily under section 25(3), and then all provisions for registered persons apply, including returns and tax payment. Small suppliers may also read our note on simplified registration under Rule 14A.
Frequently asked questions
I sell only goods in Hyderabad. Is Rs. 40 lakh my limit?
No. Telangana is excluded from the Rs. 40 lakh relief for intra-State goods suppliers, so the limit is Rs. 20 lakh.
I sell goods to another State with Rs. 5 lakh turnover. Do I need registration?
Generally yes, under section 24(i), unless a specific exemption such as the one for notified handicraft goods applies.
Do I need registration for exports?
Exports are included in aggregate turnover and are treated as inter-State supplies. Check the position for your specific supply before relying on the limit.
Is the limit per State?
No. It is computed on an all-India basis for the PAN, though registration itself is State-wise.
Sources
CGST Act, 2017, sections 2(6), 22, 24 and 25; Notification No. 10/2019-Central Tax; Notification No. 10/2017-Integrated Tax; Notification No. 5/2017-Central Tax. Thresholds are volatile, so confirm against the latest notifications before relying on this note.
This article is for general information and is not professional advice. Please obtain advice specific to your facts.
Arpan Bohra & Co., Chartered Accountants
Website: www.arpanbohra.co.in | Email: ab@arpanbohra.co.in