
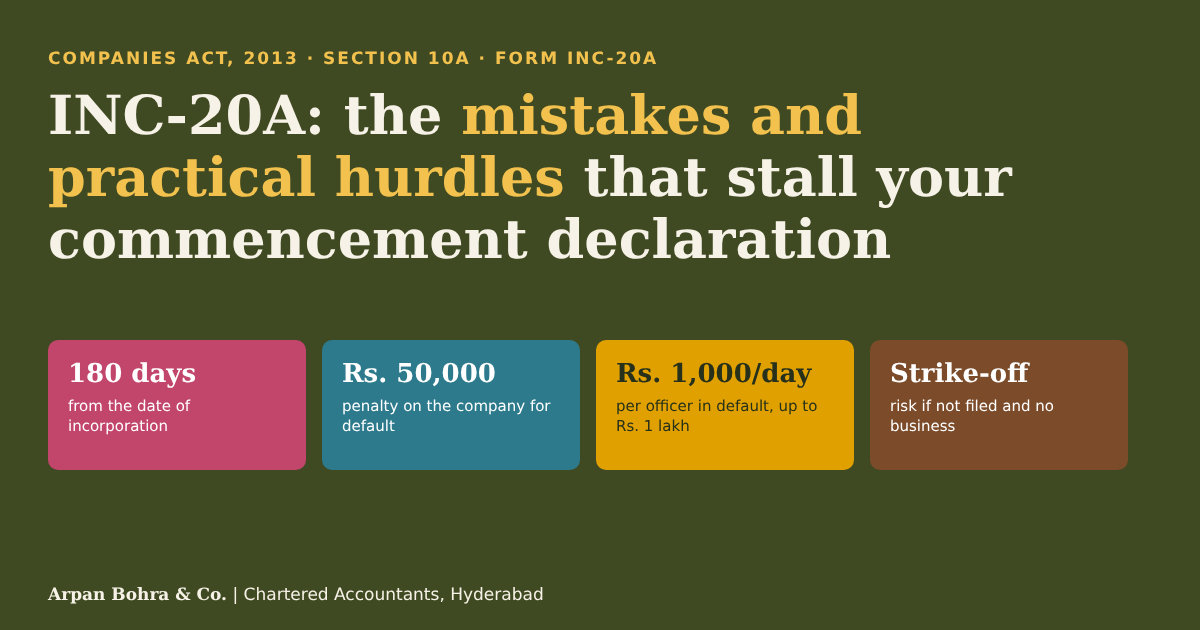
Short answer: INC-20A is the declaration, under Section 10A of the Companies Act, 2013, that every subscriber has paid for the shares he agreed to take. A company with share capital, incorporated on or after 2 November 2018, must file it within 180 days of incorporation, after verifying its registered office. Until then it may not commence business or exercise borrowing powers. Most delays come from simple, avoidable mistakes in payment trail, dates, office verification and the digital signature.
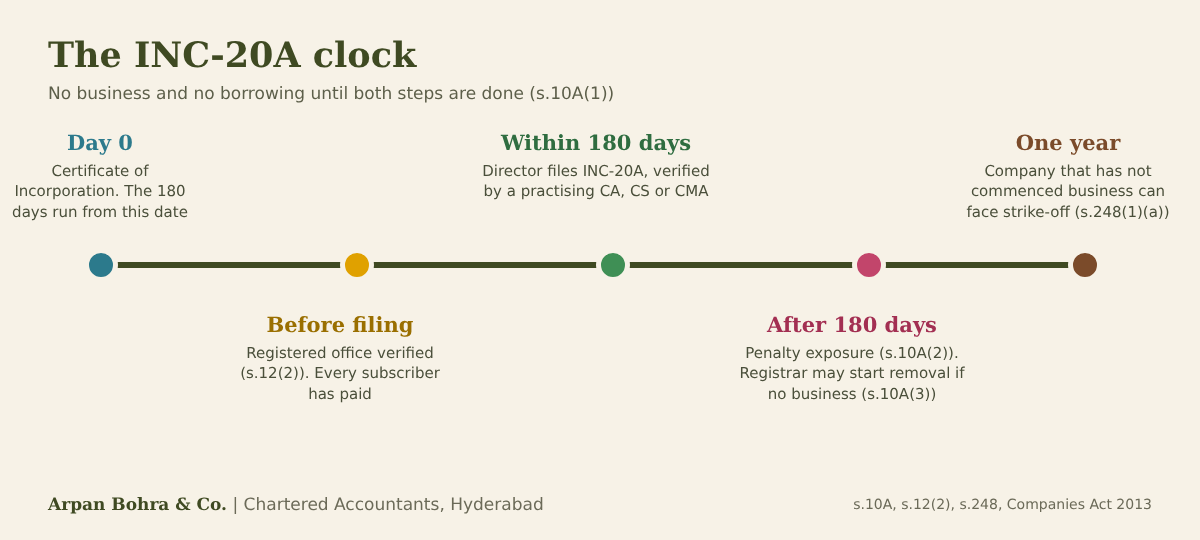
1. Who must file, and by when
Section 10A applies to a company having a share capital. A company without share capital, and a company incorporated before the section’s start (2 November 2018), is outside it. The declaration is filed by a director in Form INC-20A and, under Rule 23A, its contents are verified by a practising Company Secretary, Chartered Accountant or Cost Accountant. A company whose objects need a regulator’s registration or approval (RBI or SEBI, for example) must obtain it and attach it.
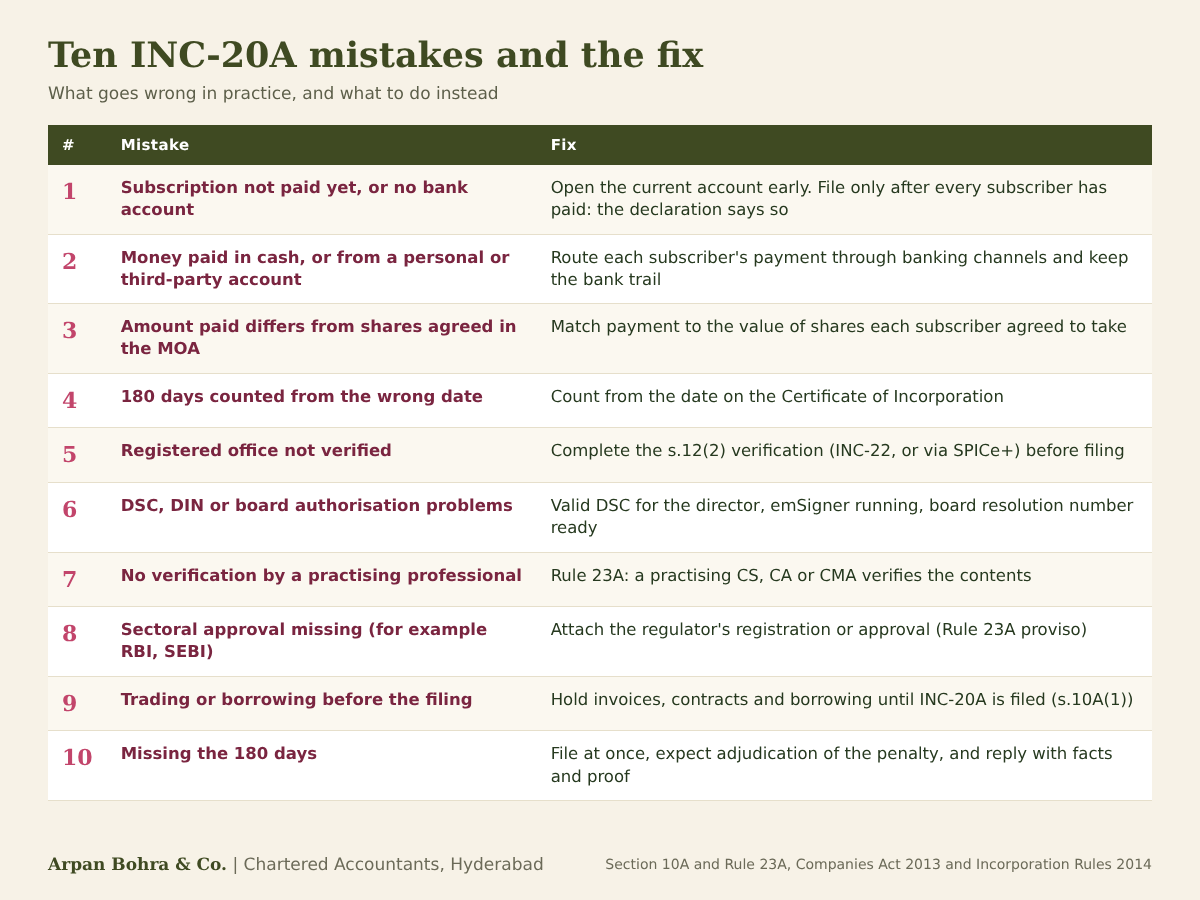
2. Ten mistakes and how to fix them
3. The practical challenges behind them
- Bank account delay. The Act gives no extension if the account opens late. The declaration must be true on the date it is made, so open the account and collect subscription money early.
- Payment trail. The form asks for each subscriber’s payment details (bank, IFSC, account, date, amount) and a bank statement is the usual proof. Money from a personal or third-party account, or in cash, invites queries from the Registrar.
- Foreign subscribers. Complete the foreign inward remittance reporting before the declaration (confirm requirements for your case).
- Registered office verification. Section 10A(1)(b) requires the Section 12(2) verification to be on file. If it was not done at incorporation, do it first (confirm the current route on the MCA portal).
- Signatures and authority. The form needs the signatory’s DSC and a Board resolution number, and false statements attract Sections 448 and 449 (the form carries this warning).
- Doing business too early. Section 10A(1) bars commencing business and exercising borrowing powers. Hold invoices, vendor contracts and loans until the filing is complete.
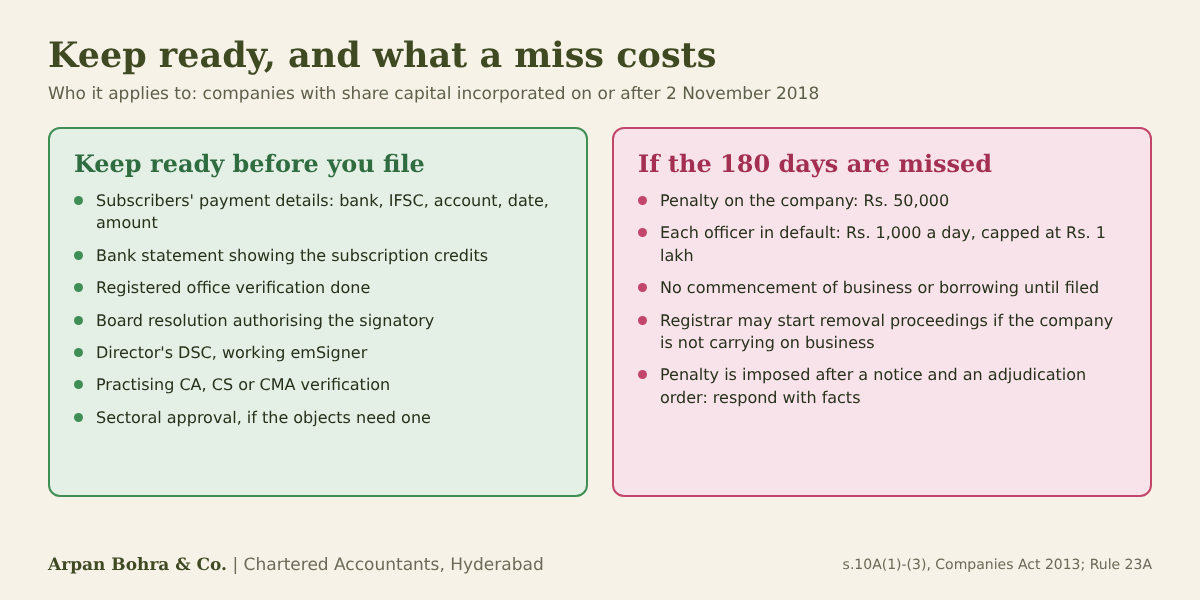
4. What to keep ready, and what a miss costs
5. If you have already missed the 180 days
- File INC-20A now. The penalty exposure under Section 10A(2) continues until the default is cured.
- Expect the penalty to be decided through a notice and an adjudication order (Section 454 process; confirm the current procedure). Prepare a reply with dates, bank evidence and the reasons for delay.
- Check whether the MCA fee schedule applies an additional filing fee for the delay (confirm).
- If you receive a strike-off notice under Section 248, the Registrar allows 30 days to respond. Section 248(1) covers a company that has not commenced business within one year and one whose subscribers have not paid and no declaration was filed within 180 days.
Founders registering startups around Hitech City, Gachibowli or the Financial District often treat incorporation as the finish line. A simple date tracker, starting from the Certificate of Incorporation, avoids the 180-day miss.
6. Common questions
Does INC-20A apply to a One Person Company? It applies to a company with share capital incorporated on or after 2 November 2018, so an OPC that fits that description is covered.
Can we start business before filing? No. Section 10A(1) bars commencing business and exercising borrowing powers until the declaration and the registered-office verification are filed.
Who signs INC-20A? A director files the declaration, authorised by the Board, with the contents verified by a practising CS, CA or Cost Accountant (Rule 23A).
What is the penalty for default? Rs. 50,000 on the company, and Rs. 1,000 for each day of continuing default on every officer in default, capped at Rs. 1 lakh for the officer (Section 10A(2)).
For what comes after commencement, see how a private limited company can distribute profits to shareholders.
Sources: Section 10A, Companies Act, 2013 (text as reproduced with its amendment history); Rule 23A, Companies (Incorporation) Fourth Amendment Rules, 2018; Section 248, Chapter XVIII; Form INC-20A, MCA. This article is for general education, not professional advice. Rules and forms change; read the law applicable to your date of incorporation before acting.
Arpan Bohra & Co., Chartered Accountants
Website: https://www.arpanbohra.co.in/
Email: ab@arpanbohra.co.in