
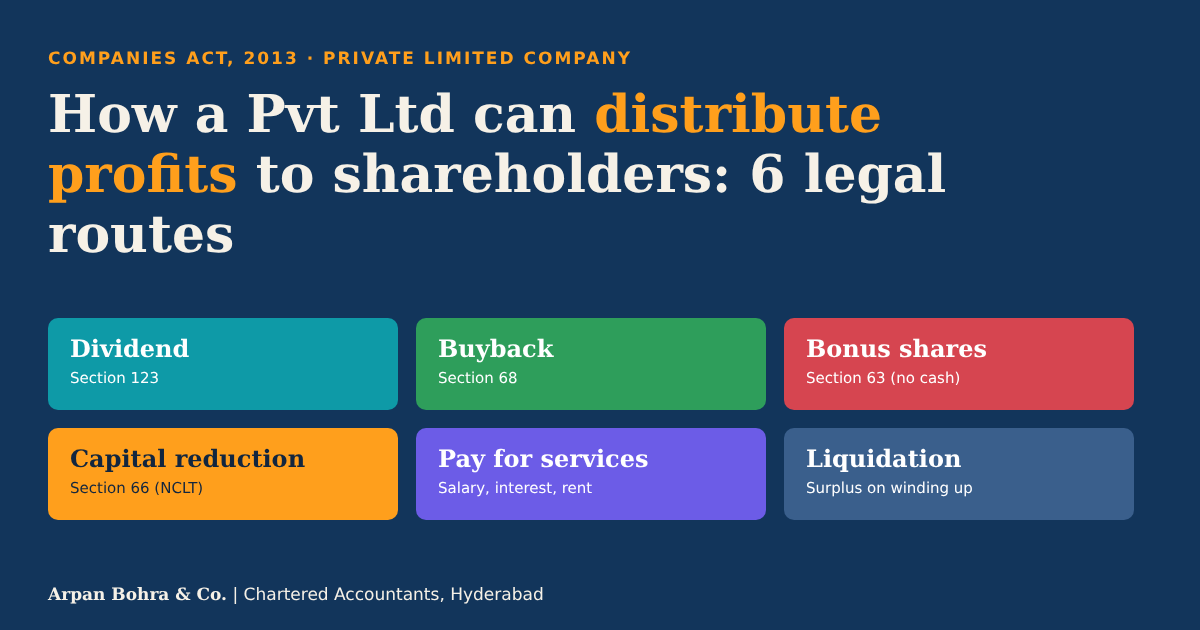
Short answer: a private limited company cannot simply move profit to shareholders’ bank accounts. The lawful routes are a dividend (Section 123, Companies Act, 2013), a buyback (Section 68), bonus shares (Section 63, no cash), a capital reduction (Section 66), payment for genuine services (salary, interest, rent) and liquidation. Each has a different legal procedure and a different tax result.
1. Six routes at a glance
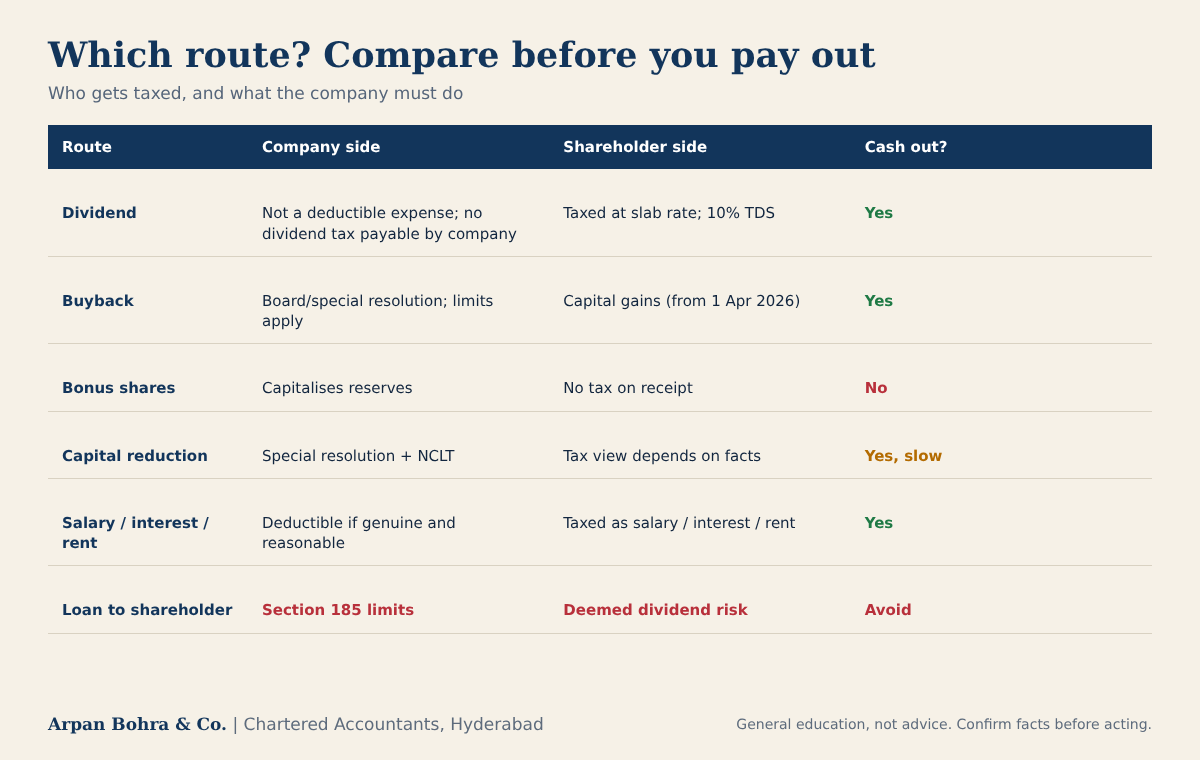
For most owner-managed companies in Hyderabad, the realistic choices are a dividend, a buyback, or fair pay for work and money the owners put in. The rest are special cases.
2. Dividend: the standard route (Section 123)
Where can the dividend come from?
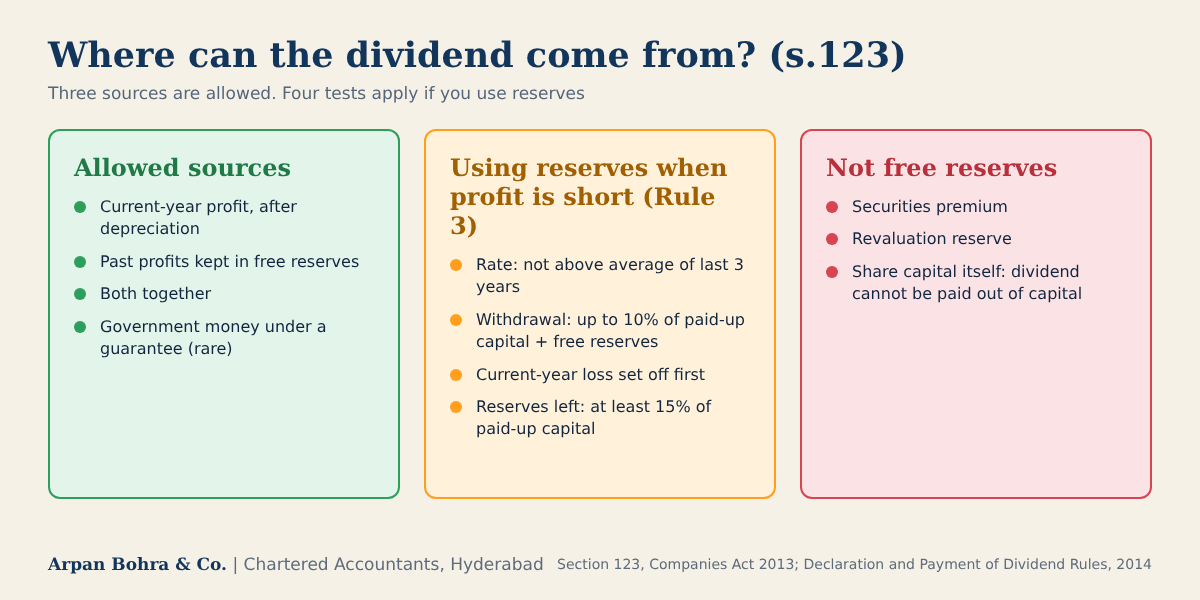
Dividend can be paid only out of (a) current-year profit after providing depreciation, (b) past profits kept in free reserves, or (c) money provided by the Government under a guarantee. If the year’s profit is short and you use reserves, the Declaration and Payment of Dividend Rules, 2014 (Rule 3) require all four: the rate is not above the average of the last three years; the amount withdrawn is not more than 10% of paid-up capital plus free reserves; the current-year loss is set off first; and reserves left are at least 15% of paid-up capital.
Final or interim
- Final dividend: recommended by the Board, approved by shareholders at the general meeting.
- Interim dividend: declared by the Board during the year, out of the surplus in the profit and loss account or current-year profit.
- Dividend is payable in cash. Bonus shares are the separate, non-cash route below.
The dividend clock
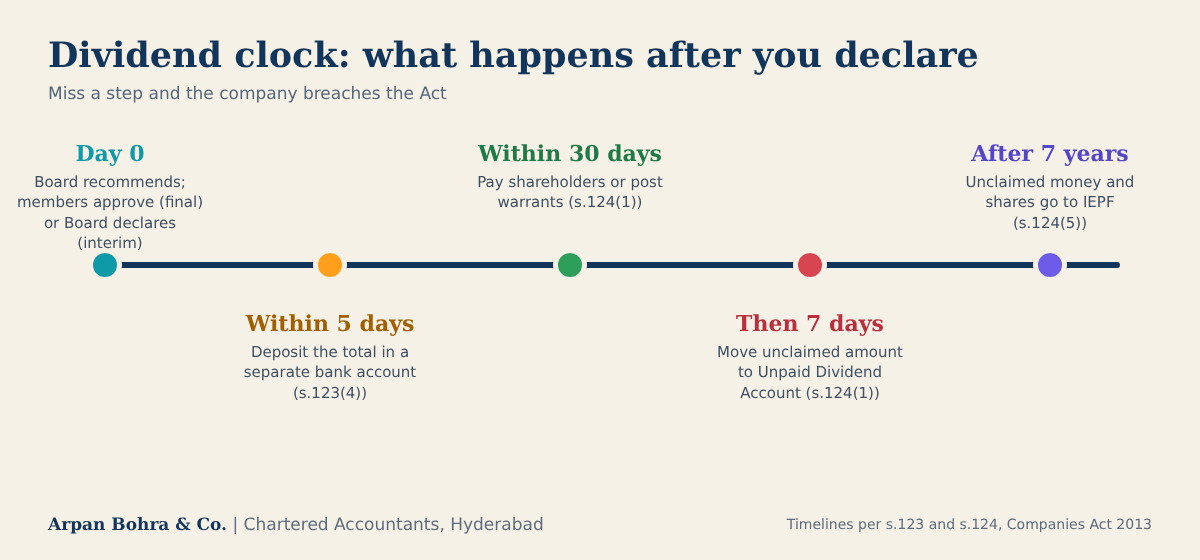
Deposit the full amount in a separate scheduled-bank account within 5 days of declaration (Section 123(4)). Pay shareholders within 30 days (Section 124(1)). Unclaimed money moves to the Unpaid Dividend Account within 7 days after that, and after 7 years it goes to the Investor Education and Protection Fund along with the shares (Section 124(5)).
3. Tax on dividend
| Who | Position |
|---|---|
| Company | No dividend distribution tax. Dividend is an appropriation of profit, not an expense. |
| Resident shareholder | Dividend is taxable income at the shareholder’s slab rate. |
| TDS | Section 393(1) of the Income-tax Act, 2025 (in force from 1 April 2026), Table Sl. No. 7: 10% with a Nil threshold, deducted before the dividend is paid. Exception: no tax is deducted from an individual shareholder if the dividend is paid by a mode other than cash and does not exceed Rs. 10,000 in the tax year (Section 393(4), Sl. 10). |
Worked example
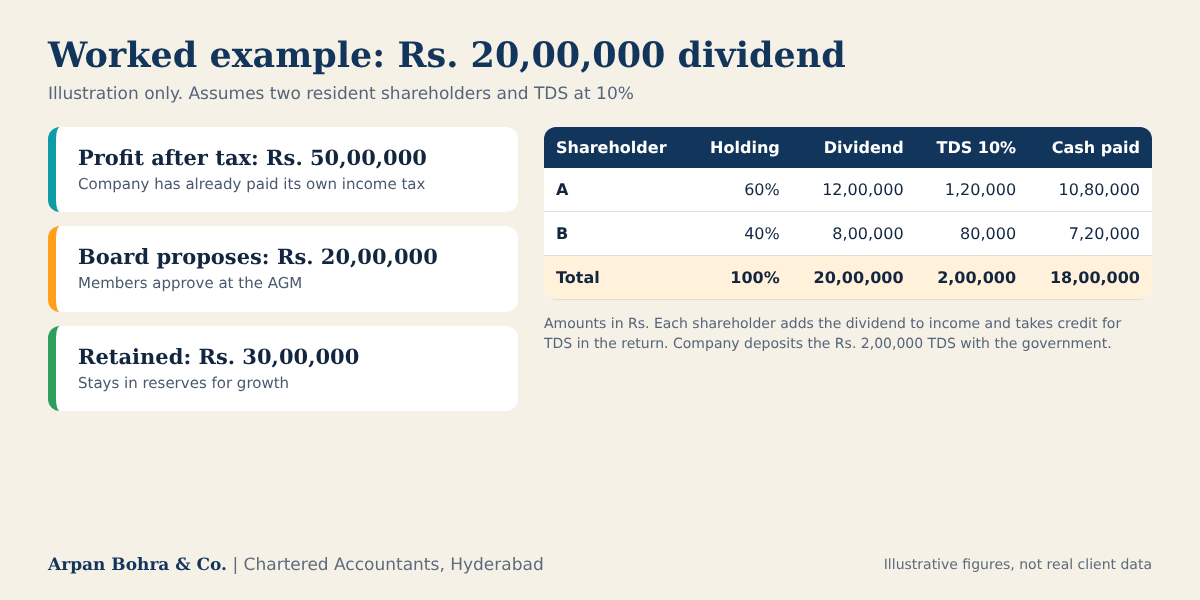
The illustration assumes both shareholders are residents and furnish PAN. The deducted tax is a credit in each shareholder’s return, and the interest deduction a shareholder claims against dividend income is capped at 20% of that dividend.
4. Buyback (Section 68)
The company buys its own shares and pays the shareholder. Key conditions: it can be funded from free reserves, securities premium or proceeds of an earlier issue of other shares (not the same kind of shares); buyback in a year is capped at 25% of paid-up capital plus free reserves; a Board resolution suffices up to 10%, above that a special resolution is needed; and post-buyback debt-to-equity cannot exceed 2:1. Another buyback cannot follow within one year.
Tax: from 1 October 2024 buyback proceeds were taxed as deemed dividend. From 1 April 2026 the Budget 2026 change taxes the shareholder on capital gains instead (sale price minus cost). For the capital-gains rates see our article on tax rates on shares.
5. Bonus shares (Section 63)
Free reserves, securities premium or the capital redemption reserve can be converted into fully paid shares for existing holders. Nobody receives cash. Value moves into share capital, so use it to reward holders without draining cash, not to fund their expenses.
6. Capital reduction (Section 66)
Where capital is surplus to need, the company may return it, but this needs a special resolution, confirmation by the National Company Law Tribunal (NCLT) and creditor safeguards. It is slow and costly, so it suits one-off restructuring, not annual payouts. The tax position depends on how the transaction is structured: take advice before filing.
7. Pay for work and money put in
Owners who work in the company can draw remuneration, and owners who lend to it can earn interest or rent on property they let to it. These are deductible to the company only when genuine, supported by an agreement and reasonable for the work or loan, and are taxed in the owner’s hands under the respective head. TDS applies to each payment. Disguising profit as inflated salary invites disallowance.
8. Liquidation
On winding up, what is left after creditors are paid goes to shareholders according to their rights. This ends the business, so it is a closure route, not a distribution plan.
9. The trap: taking a “loan” instead
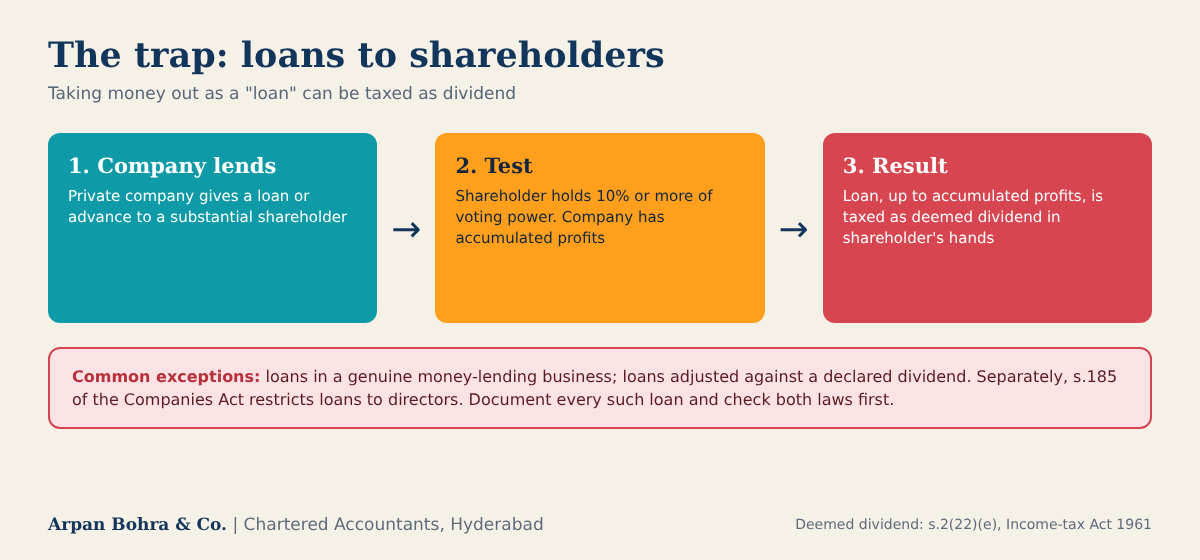
Under the deemed dividend rule (Section 2(22)(e) of the Income-tax Act, 1961, carried into the 2025 Act), a loan or advance from a closely held company to a shareholder holding 10% or more of the voting power is taxed as dividend, up to the company’s accumulated profits. Genuine money-lending business loans and loans adjusted against a declared dividend are among the recognised exceptions. Separately, Section 185 of the Companies Act restricts loans to directors. Paper every shareholder loan, and check both laws first.
10. Checklist before you pay out
- Confirm distributable profits and free reserves from audited accounts.
- Pick the route: dividend, buyback or pay for services.
- Pass the right resolution (Board and, where needed, shareholders).
- Deposit within 5 days; pay within 30 days.
- Deduct TDS and file the return on time.
- Keep minutes, bank proof and a note of the legal basis.
11. Common questions
Can a private company pay dividend in a loss year? Only out of reserves and only if all four Rule 3 conditions are met.
Is dividend tax-free for the shareholder? No. A resident shareholder pays tax at the slab rate, and TDS is deducted at source above the threshold.
Can the company pay dividend out of share capital? No.
This article is for general education and is not professional advice. Facts, amendments and the structure of each company differ. Read the law applicable to your transaction date before acting.
Arpan Bohra & Co., Chartered Accountants
Website: https://www.arpanbohra.co.in/
Email: ab@arpanbohra.co.in