
Short answer: under the Income-tax Act, 2025 (in force from 1 April 2026), salary TDS sits in Section 392 and almost every other TDS rate sits in Section 393, in three tables: payments to residents, to non-residents and to any person. The chart below shows each Section 393 entry with its threshold, rate and the Income-tax Act, 1961 section it replaces.
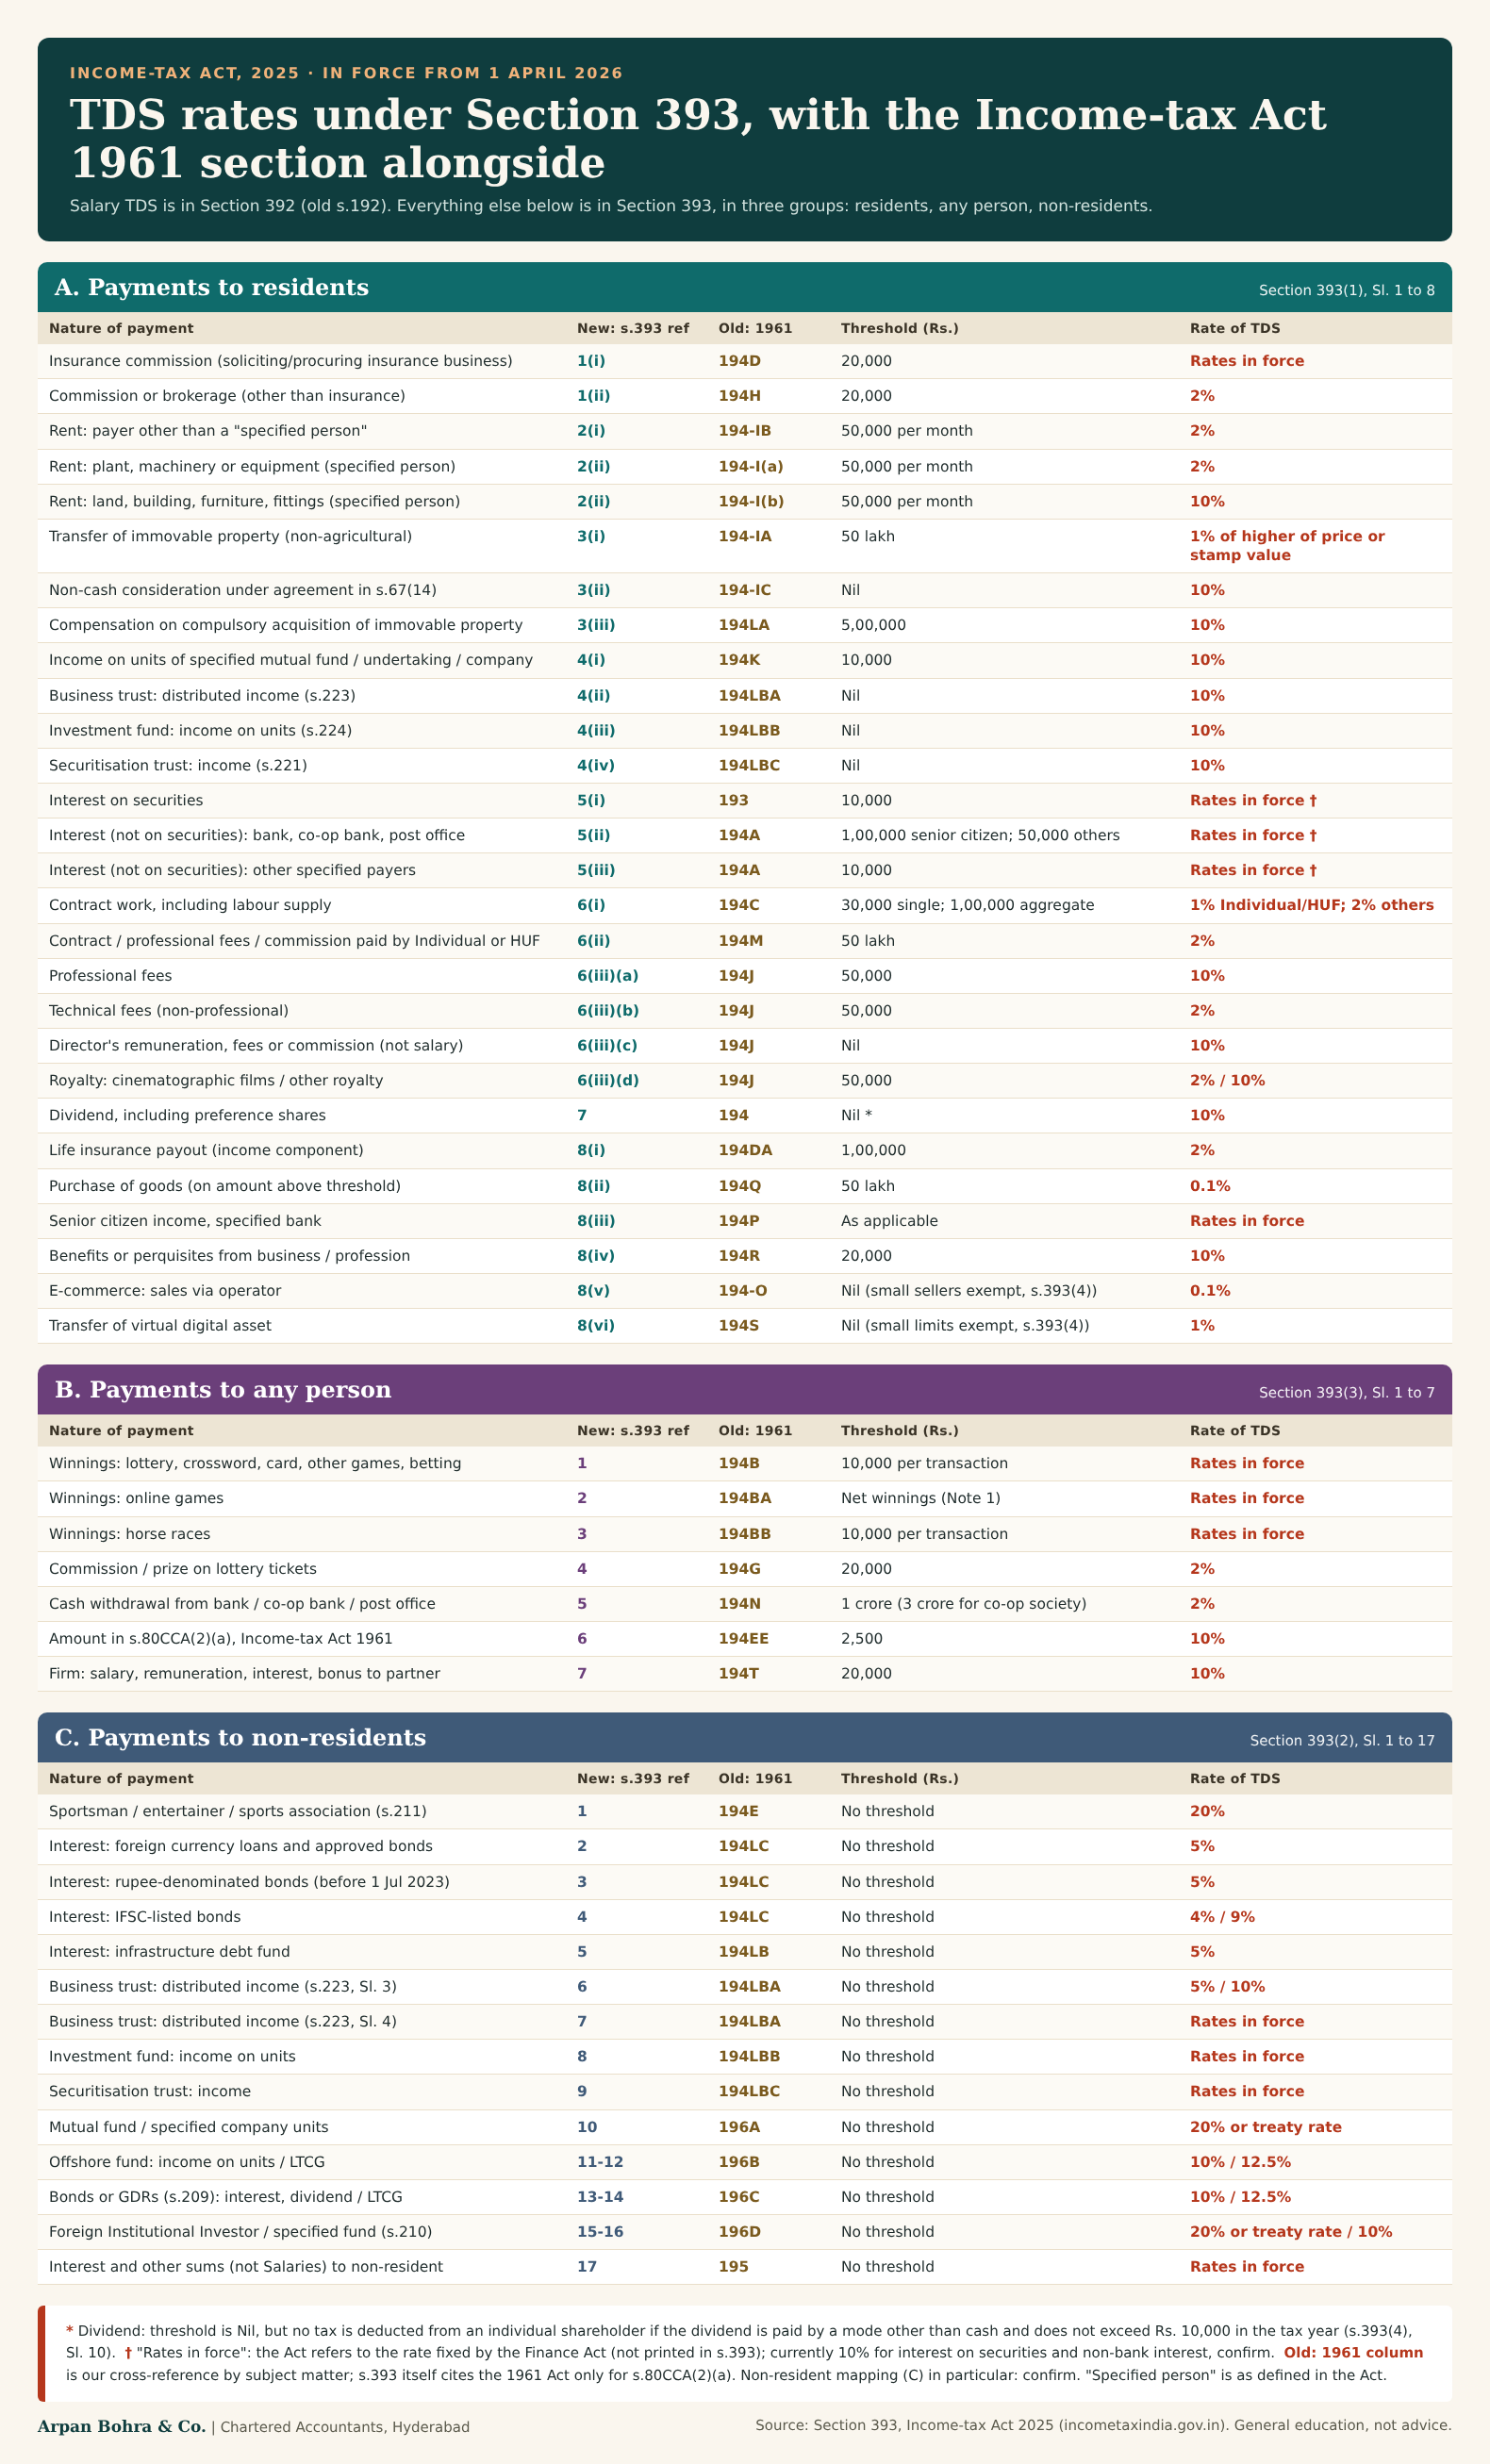
Click the image to open it in full size.
The most-used entries in text form
| Payment | s.393 (2025 Act) | 1961 Act | Threshold | Rate |
|---|---|---|---|---|
| Contract work | (1), Sl. 6(i) | 194C | Rs. 30,000 single; Rs. 1,00,000 aggregate | 1% Individual/HUF; 2% others |
| Commission or brokerage | (1), Sl. 1(ii) | 194H | Rs. 20,000 | 2% |
| Rent: plant, machinery | (1), Sl. 2(ii) | 194-I(a) | Rs. 50,000 per month | 2% |
| Rent: land, building, furniture | (1), Sl. 2(ii) | 194-I(b) | Rs. 50,000 per month | 10% |
| Professional fees | (1), Sl. 6(iii)(a) | 194J | Rs. 50,000 | 10% |
| Technical fees | (1), Sl. 6(iii)(b) | 194J | Rs. 50,000 | 2% |
| Dividend | (1), Sl. 7 | 194 | Nil (see note) | 10% |
| Transfer of immovable property | (1), Sl. 3(i) | 194-IA | Rs. 50 lakh | 1% |
| Purchase of goods | (1), Sl. 8(ii) | 194Q | Rs. 50 lakh | 0.1% |
| Benefits or perquisites | (1), Sl. 8(iv) | 194R | Rs. 20,000 | 10% |
| Virtual digital assets | (1), Sl. 8(vi) | 194S | Nil (small limits exempt) | 1% |
| Payment to firm’s partner | (3), Sl. 7 | 194T | Rs. 20,000 | 10% |
What to watch
- Dividend: the threshold is Nil, but no tax is deducted from an individual shareholder when the dividend is paid by a mode other than cash and does not exceed Rs. 10,000 in the tax year (Section 393(4), Sl. 10).
- “Rates in force”: for interest, insurance commission, winnings and several other entries, Section 393 refers to the rate fixed by the Finance Act, so the percentage is not printed in the section.
- “Specified person”: the payer category that decides which rent and fee entry applies. Read the definition in the Act before choosing the row.
- 1961 references: Section 393 itself does not print them (except Section 80CCA(2)(a)). The 1961 column is our cross-reference by subject matter, so confirm the non-resident rows in particular.
For how dividend TDS applies in practice, see how a private limited company can distribute profits.
Source: Section 393, Income-tax Act, 2025, Income Tax Department. This article is for general education, not professional advice. Rates and thresholds change; read the law applicable to the payment date before deducting tax.
Arpan Bohra & Co., Chartered Accountants
Website: https://www.arpanbohra.co.in/
Email: ab@arpanbohra.co.in