
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Know the ladder before you step on it: APL-01, GSTAT, High Court.
After an adverse order, the first question is not on merits but on timing and money: how many days remain, and how much must be deposited to appeal? The GST appeal route has three steps before the Supreme Court, each with its own limitation, forum and pre-deposit.
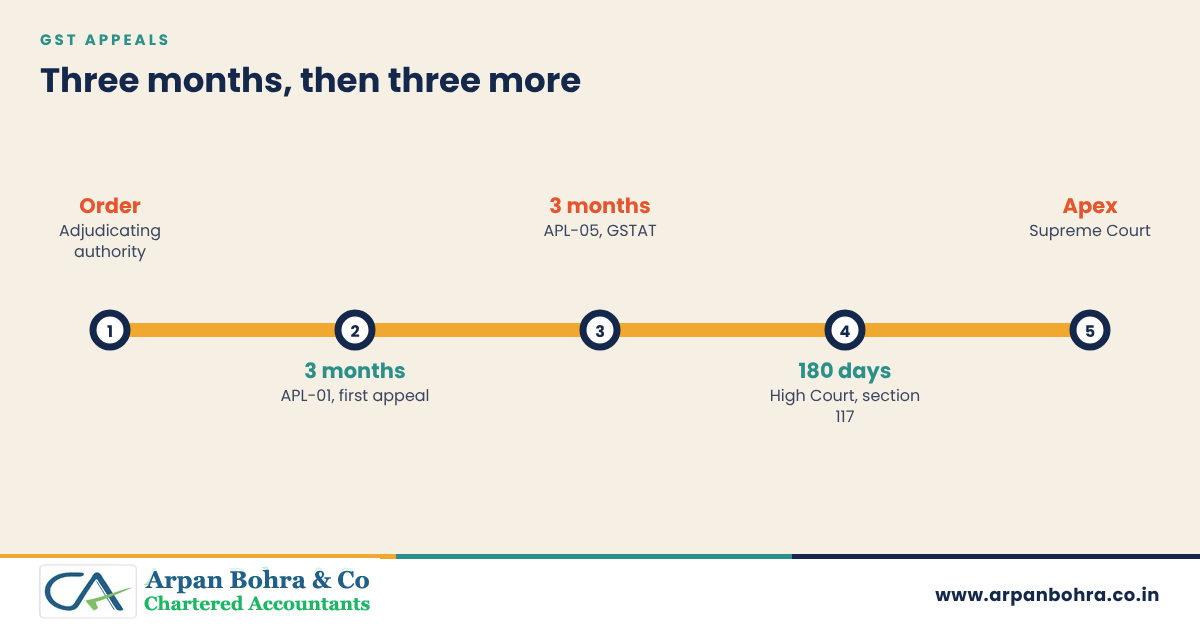
An order of an adjudicating authority is appealed to the first appellate authority in Form APL-01 under section 107 within three months, with a pre-deposit of 10% of the disputed tax (subject to the statutory cap). A second appeal lies to the GST Appellate Tribunal (GSTAT) in Form APL-05 under section 112 within three months, with a further pre-deposit of 10% of the remaining disputed tax subject to a cap (verify the cap and the transitional rules). A High Court appeal on a substantial question of law lies under section 117. Pre-deposit and limitation figures should be verified against the current text.
The ladder
| Stage | Forum and form | Limit | Pre-deposit |
|---|---|---|---|
| First appeal | Appellate authority, APL-01 (section 107) | Three months from communication of the order; condonation up to one more month | Full admitted tax and 10% of the disputed tax, subject to the cap in section 107(6) (verify the cap) |
| Second appeal | GSTAT, APL-05 (section 112) | Three months from communication of the appellate authority’s order; extendable by three months | Admitted tax plus 10% of the remaining disputed tax, subject to a cap (verify); balance recovery stayed (section 112(9)) |
| High Court | Appeal on substantial question of law (section 117) | 180 days from the date of receipt of the Tribunal order | None prescribed; costs and stays by court order |
| Supreme Court | Appeal under section 118 | Under the Supreme Court Rules and the Act | As directed |
Points that decide the appeal
- Count from communication, not from the date of the order, and keep proof of upload and service.
- Pre-deposit is paid from the cash ledger or credit through DRC-03, and the electronic credit ledger cannot be used for the pre-deposit (verify Rule 85 and the circulars).
- Recovery stays automatically on payment of the pre-deposit; the stay of the balance demand is stated in the Act.
- Grounds and record. The Tribunal will largely rely on the record, and new evidence needs permission, so the first appeal should contain all the facts.
- GSTAT operations. The Tribunal’s benches and filing portal have been brought into operation, and transitional directions on older orders were issued; confirm the applicable limitation for your order (litigative).
Worked example
An order demands tax of ₹1 crore, interest and penalty. The taxpayer admits ₹10 lakh of tax.
- First appeal: pre-deposit is ₹10 lakh admitted tax plus 10% of the remaining ₹90 lakh, which is ₹9 lakh, a total of ₹19 lakh, subject to the cap.
- If the first appellate authority confirms the demand, a second appeal to GSTAT requires a further 10% of the remaining disputed tax, which is ₹9 lakh again on the unpaid balance, subject to the cap and the rules on adjustment of amounts already paid (verify).
- High Court: only on a substantial question of law and within 180 days.
Strategy
| Question | View | Risk |
|---|---|---|
| Delay in filing | File within limitation; condonation is limited and the Tribunal may refuse extension | High if delayed |
| Penalty-only matters | Check if the 57th Council’s recommendation for penalty-only pre-deposit applies; it is not yet law | Litigative |
| Writ instead of appeal | High Courts entertain writs for jurisdictional errors or natural justice, but alternate remedy is usually insisted upon | Moderate to high |
| Seeking stay of balance | Section 112(9) stays recovery of the balance after pre-deposit | Low |
Frequently asked questions
What is the time limit for a first appeal in GST?
What pre-deposit is required for the first appeal?
What is APL-05?
Can I use input tax credit for the pre-deposit?
Can the High Court be approached directly?
Is the 57th Council’s pre-deposit proposal in force?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.