
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
A good reply to a show cause notice is built on three files, not one letter.
A manufacturer receives a show cause notice for ₹80 lakh with a hearing three weeks away. The facts are simple, but the quality of the reply decides whether the order is dropped or the matter goes to appeal. The reply is the only chance to build the record for the first appellate authority and the Tribunal.
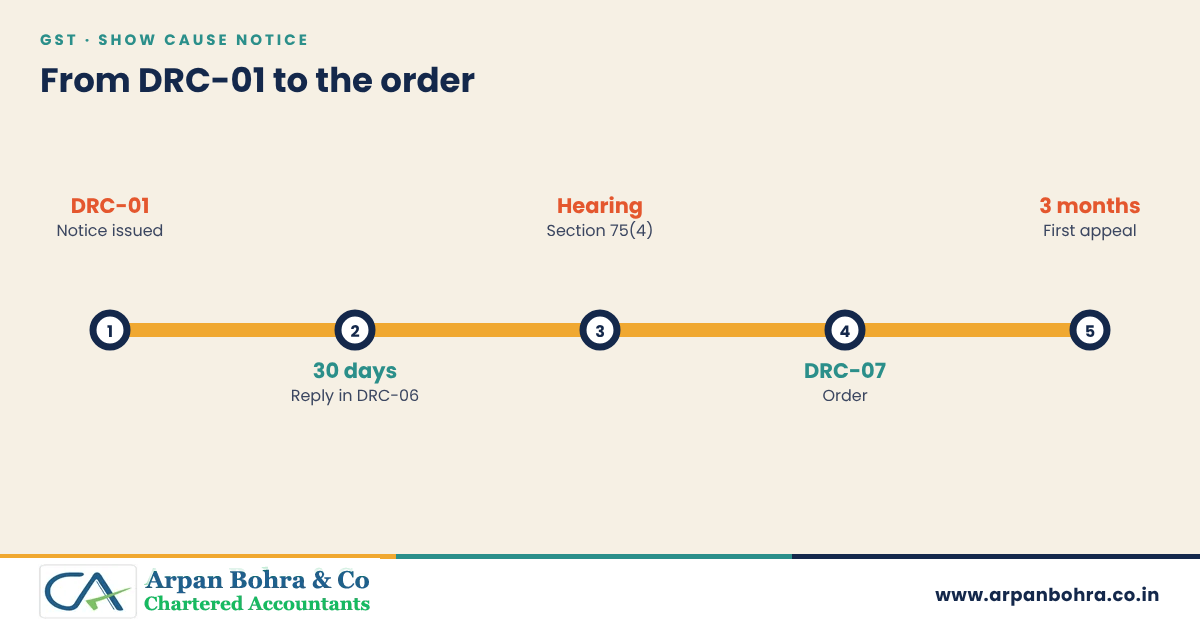
A GST show cause notice (SCN) is issued in Form GST DRC-01 under section 73, 74 or 74A, and the reply is filed in Form GST DRC-06 within the period stated, usually 30 days (Rule 142(4)). Section 75 requires the officer to grant a personal hearing where adverse action is proposed, to consider the reply, to confine the order to the grounds in the notice, and to pass the order within the time limit. A reply should combine preliminary objections (jurisdiction, limitation, vague notice, procedural defects) with a merits response and supporting documents.
Time limits
| Provision | Notice | Order |
|---|---|---|
| Section 73 (non-fraud, up to FY 2023-24) | At least three months before the order time limit | Within three years of the annual return due date |
| Section 74 (fraud etc., up to FY 2023-24) | At least six months before the order time limit | Within five years of the annual return due date |
| Section 74A (FY 2024-25 onwards) | Within 42 months of the annual return due date | Within 12 months of the notice, extendable by up to six months with reasons |
Verify the periods for the relevant year, including notified extensions for earlier years.
Structure of a strong reply
- Facts and background. Business, registration, the period and the transaction.
- Preliminary objections. Limitation, jurisdiction of the officer, absence of DIN on the notice where required (Circular 122/41/2019, verify), vague or composite grounds, reliance on undisclosed material, and wrong section.
- Merits. Ground-by-ground reply with computation and documents.
- Law. Provisions, circulars and rulings, with only those that bind or persuade in the jurisdiction.
- Prayer. Drop the proceedings, grant a personal hearing, supply the relied-upon documents and reserve the right to supplement the reply.
Procedural rights to invoke
- Personal hearing under section 75(4) where an adverse decision is contemplated or the person requests it.
- Up to three adjournments under section 75(5).
- Order to be confined to the grounds in the notice and the amount not to exceed the notice amount (section 75(7) and (8)).
- Order in Form DRC-07 with the reasons, and a summary of the order in DRC-07 for the demand.
- Documents relied upon must be furnished; ask in writing.
Worked timeline
An SCN for FY 2023-24 is uploaded on 1 September 2026 with a hearing on 28 September 2026.
- Reply in DRC-06 within 30 days: by 1 October 2026, and preferably before the hearing.
- Request documents on day 3, and a copy of the investigation report.
- Attend the hearing, file written submissions and a compilation.
- The order is due within three years from the annual return due date for FY 2023-24 under section 73 (verify the extended date). A first appeal lies within three months of the order.
Risk and strategy
| Issue | Primary position | Risk |
|---|---|---|
| Fraud alleged under section 74 | Contest the allegation of fraud, suppression or wilful misstatement; the department must show intent | Moderate to high |
| Cryptic SCN | Challenge as violating natural justice and Rule 142(1) | Low to moderate |
| Pay under DRC-03 before the order | Closes the matter without penalty in non-fraud cases; consider where the claim is weak | Low |
| Reply not filed | Ex parte order and loss of the chance to build the record | High |
Frequently asked questions
What is the time limit for replying to a GST SCN?
Is a personal hearing mandatory?
Can the order exceed the SCN amount?
What if the SCN has no DIN?
Can I pay and close the matter?
Where do I appeal?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.