
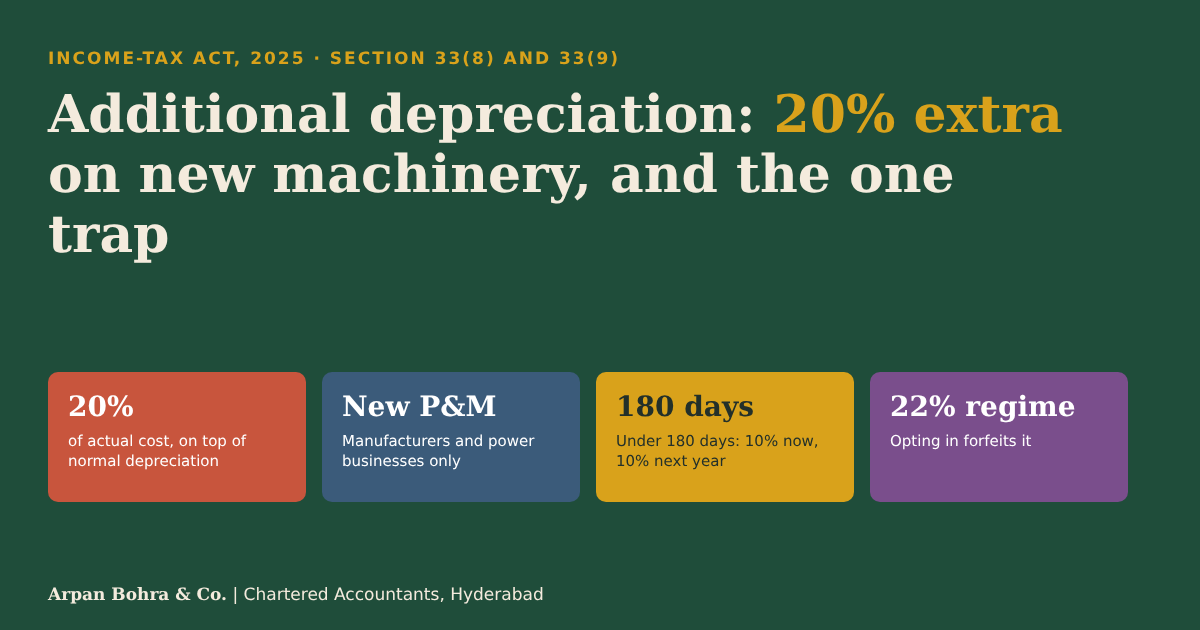
Short answer: a manufacturer that buys new plant and machinery can claim additional depreciation of 20% of its actual cost, over and above normal depreciation (Section 33(8) and (9), Income-tax Act, 2025, in force from 1 April 2026; earlier Section 32(1)(iia) of the 1961 Act). If the machine is used for less than 180 days in the first year, it is split 10% now and 10% next year. Opting for the 22% concessional corporate-tax regime switches it off.
1. Who qualifies?
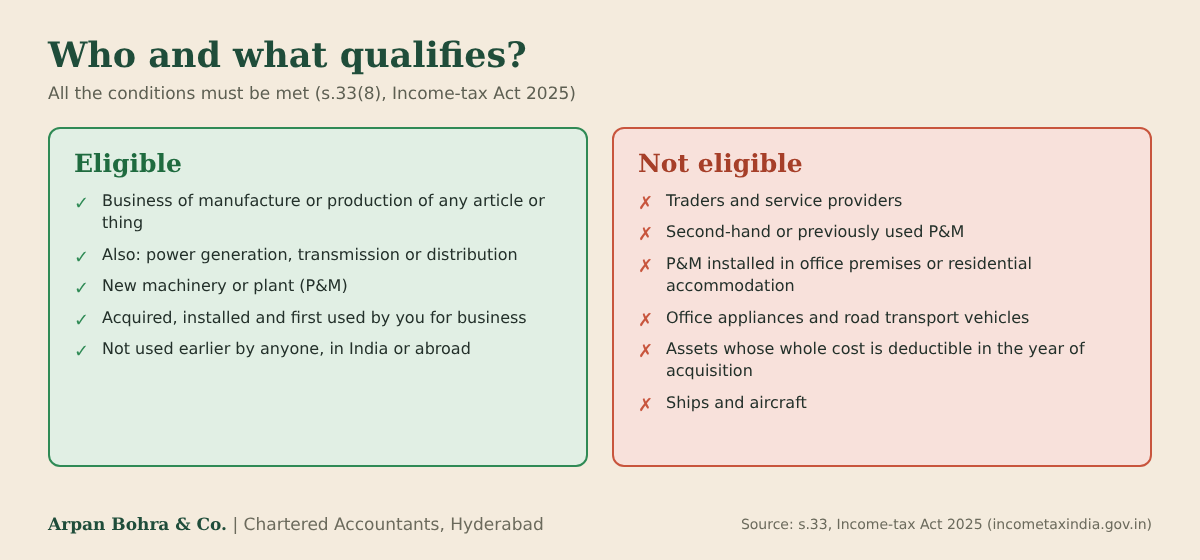
The business must be manufacture or production of any article or thing (power generation, transmission or distribution is also covered). The machinery or plant must be new: acquired, installed and first used by you for business, and never used by anyone else, in India or abroad. Traders and service providers are outside the benefit. A unit in Hyderabad’s industrial areas such as Jeedimetla, Patancheru or Pashamylaram that buys a new production line fits the profile; a showroom’s air-conditioner does not.
2. How much, and when?
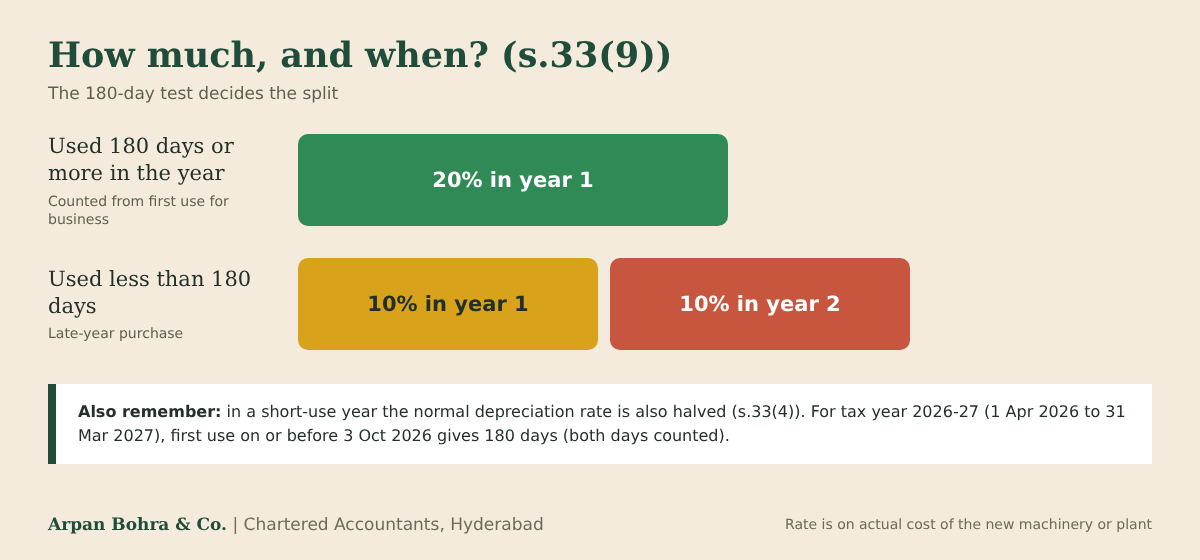
- Used for 180 days or more: 20% of actual cost in the tax year it is acquired and put to use.
- Used for less than 180 days: 10% that year, and the remaining 10% in the next tax year. Normal depreciation is also halved for that year (s.33(4)).
- For tax year 2026-27, first use on or before 3 October 2026 gives 180 days (both days counted).
3. Worked example

Machine A is put to use well before the cut-off, so it earns the full 20%. Machine B, used for only 107 days, earns 10% now and 10% next year. Actual cost excludes GST for which you claim input tax credit (confirm for your case).
4. The trap: the 22% regime
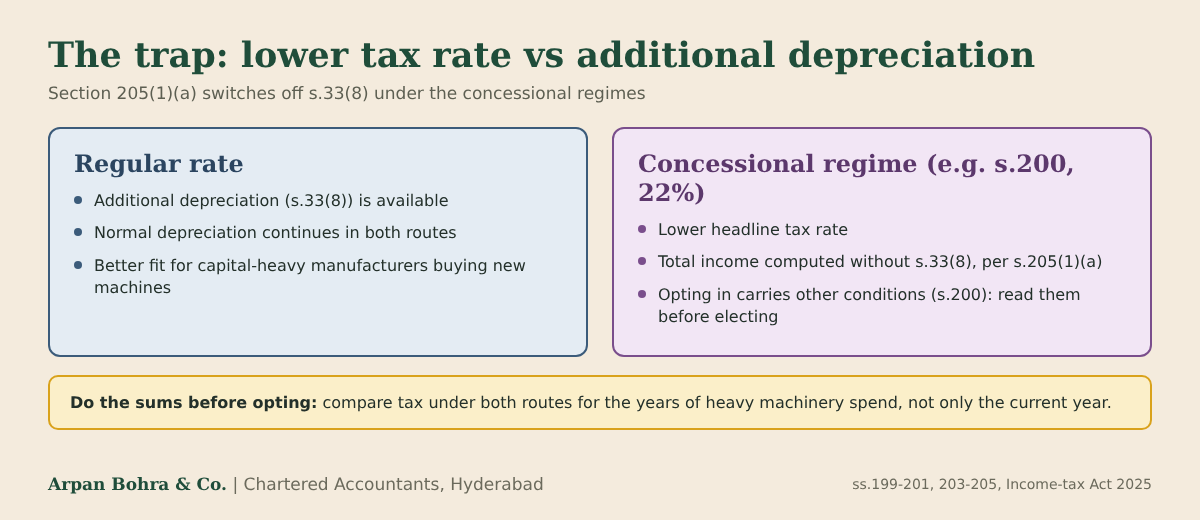
Under Section 205(1)(a), total income under the concessional regimes (Sections 199, 200, 201, 203 and 204) is computed without the deduction under Section 33(8). A company planning heavy machinery spend should compare tax under both routes before opting in, because a lower rate can cost more than it saves in an investment year.
5. Common mistakes
- Claiming on used or imported-second-hand machinery.
- Installing the asset in office premises or residential accommodation.
- Claiming on office appliances or vehicles.
- Forgetting the second-year 10% on a late-year purchase.
- Not keeping proof of first use (invoice, commissioning record, power connection date).
- Electing the concessional regime without modelling the lost deduction.
6. Books versus tax
Additional depreciation is a tax deduction. It does not change depreciation in the books, so the gap is a timing difference to track for deferred tax.
7. What about the 35% rate for Andhra Pradesh and Telangana?
Earlier law gave 35% for new machinery in notified backward areas of Andhra Pradesh and Telangana, but only for assets acquired in the window from 1 April 2015 to before 1 April 2020. We found no equivalent in the current Section 33, so treat 20% as the rate for new acquisitions.
Checklist before you claim
- Confirm the business is manufacture, production or power.
- Confirm the machine is new and not an excluded asset.
- Record the date of first use for business.
- Count days to 31 March and apply 20% or 10% + 10%.
- Check you have not opted into a concessional regime.
If your company’s profits are being distributed to owners, read how a private limited company can distribute profits.
Source: Section 33, Income-tax Act, 2025, Income Tax Department. This article is for general education, not professional advice. Facts and the law applicable to your transaction date differ; read the law before acting.
Arpan Bohra & Co., Chartered Accountants
Website: https://www.arpanbohra.co.in/
Email: ab@arpanbohra.co.in