
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Pay MSME suppliers on time, or lose the deduction.
A Hyderabad manufacturer buys components worth ₹10 lakh from a small enterprise on 1 March and pays in May. The expense is booked in March, but the tax deduction for March may not be available. Section 43B(h) of the Income-tax Act, 1961 ties the deduction for amounts owed to micro and small enterprises to the time limits in the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006.
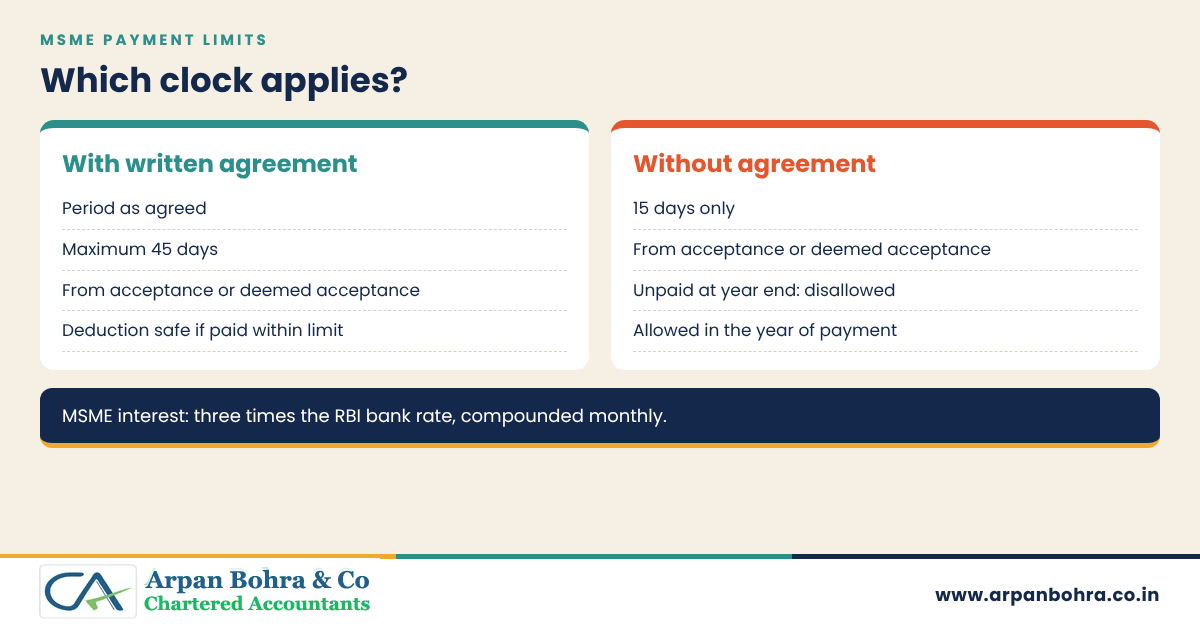
Under section 43B(h), an amount payable to a micro or small enterprise that remains unpaid beyond the time allowed by section 15 of the MSMED Act is deductible only in the year it is actually paid. Section 15 allows the period agreed in writing, which cannot exceed 45 days from the day of acceptance or deemed acceptance, or 15 days where there is no written agreement. Medium enterprises are outside the clause. For tax years under the Income-tax Act, 2025 the same rule continues in a corresponding provision (verify the section number).
Who is covered
- The supplier must be a micro or small enterprise, which is registered on the Udyam portal. A medium enterprise is not covered.
- Registration should exist on the date of supply; the position where the supplier registers later is debated, so obtain the Udyam certificate before ordering.
- The clause applies to supplies of goods or services. Whether purchases from a trader-category Udyam supplier are within section 15 of the MSMED Act is a litigative point (verify current CBDT clarifications).
The 15-day and 45-day limits
| Situation | Time limit under section 15, MSMED Act |
|---|---|
| Written agreement fixing a date | As agreed, but not more than 45 days from acceptance or deemed acceptance |
| No written agreement | 15 days from acceptance or deemed acceptance |
| Goods rejected or objection raised within 15 days | Acceptance is counted from the day the objection is resolved or from the day of delivery as the Act provides (verify) |
Acceptance means the day of actual delivery of goods or rendering of services; deemed acceptance applies when no objection is made in writing within 15 days.
What happens if you pay late
| Item | Position |
|---|---|
| Tax deduction | Disallowed in the year of accrual to the extent unpaid beyond the limit; allowed in the year of actual payment |
| Relief up to the due date of the return | The extended-payment relief in the proviso to section 43B does not apply to clause (h) (verify the current proviso) |
| Interest under MSMED Act, section 16 | Compound interest with monthly rests at three times the bank rate notified by the RBI |
| Interest under the MSMED Act in the accounts | Not deductible for the buyer under section 23 of the MSMED Act |
| Disclosure | Overdue MSME dues are reported in the financial statements and in the MSME Form 1 filing with the Registrar (verify the current requirement) |
Worked example
A company buys goods worth ₹10,00,000 from a small enterprise on 1 March 2026, accepted the same day.
- No written agreement: the 15-day limit ends 16 March. If ₹10,00,000 remains unpaid on 31 March 2026, the deduction for that purchase cost is disallowed in FY 2025-26 and allowed in the year of payment.
- Written agreement for 45 days: the limit ends 15 April 2026, after the year-end. The amount is not yet beyond the time limit on 31 March, so no disallowance arises for FY 2025-26 on this view; it is a point to confirm.
- Interest: if payment is delayed beyond the limit, the supplier may claim interest under section 16 of the MSMED Act.
Compliance steps
- Tag every vendor as micro, small, medium or non-MSME using the Udyam certificate.
- Get a written payment agreement with a period of 45 days or less.
- Track acceptance dates, not invoice dates.
- Run a vendor ageing report before each quarter-end and before 31 March.
- Compute the disallowance in the return and report overdue dues in the tax audit report, clause 22 of Form 3CD (verify the current clause number).
- Pay the oldest MSME dues first if the year-end cash is limited.
Frequently asked questions
Does section 43B(h) apply to medium enterprises?
Is the 45-day limit counted from the invoice date?
Can I claim the deduction if I pay before the return due date?
What interest can an MSME supplier claim?
Does the rule apply from FY 2023-24?
What about the Income-tax Act, 2025?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.