
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Most income tax notices start with an avoidable error.
A salaried taxpayer files the return from Form 16 alone and later receives an intimation under section 143(1) proposing additional tax because interest income and a share sale reported in the Annual Information Statement (AIS) were missed. The error took ten minutes to make and several weeks to resolve. Most notices follow a small group of repeated mistakes.
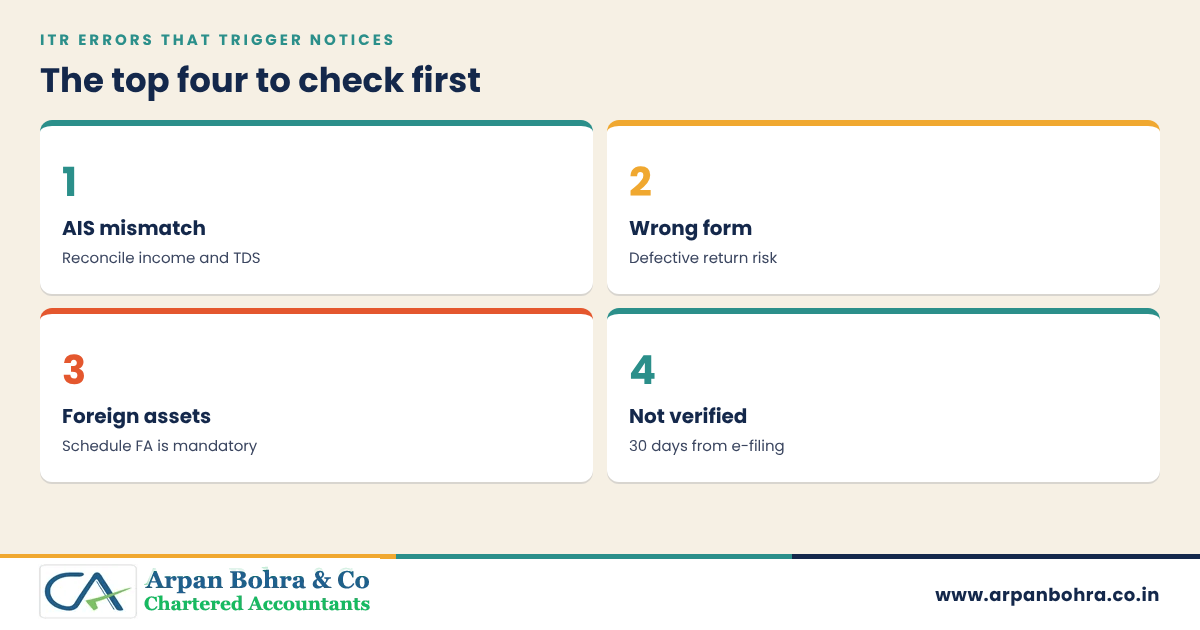
The most common causes of income tax notices are a mismatch with AIS, Form 26AS or TDS data, the wrong ITR form, undisclosed capital gains or foreign assets, deductions claimed without proof, an unverified return (it must be verified within 30 days of e-filing) and wrong refund bank details. A belated or revised return for FY 2025-26 can generally be filed until 31 December 2026 (verify the current due dates). This article applies to returns for FY 2025-26 under the Income-tax Act, 1961.
The ten mistakes
| # | Mistake | Why it matters | Fix |
|---|---|---|---|
| 1 | Ignoring AIS and Form 26AS | Mismatch triggers an intimation or notice | Reconcile income and TDS before filing |
| 2 | Wrong ITR form | The return can be treated as defective under section 139(9) | Choose the form by income type and residency |
| 3 | Not reporting capital gains | Share and mutual fund sales appear in AIS | Report every sale, and use the correct holding period and rates |
| 4 | Not reporting foreign assets and income | Schedule FA is mandatory for residents; the Black Money Act carries penalty (verify the current amount) | Disclose all overseas accounts, shares and ESOPs |
| 5 | Claiming deductions without proof | HRA, 80C and 80D claims are verified on scrutiny | Keep rent receipts, premium receipts and PAN of the landlord where required |
| 6 | Not verifying the return | An unverified return is treated as not filed | E-verify within 30 days of filing |
| 7 | Wrong bank account for refund | Refund fails or is delayed | Pre-validate the account on the portal |
| 8 | Under-reporting exempt income | Exempt income must be disclosed in the schedule | Report interest on PPF, dividends and agricultural income correctly |
| 9 | Missing the filing date | Late fee under section 234F and loss of carry-forward of certain losses | File on time; losses need a return filed by the due date |
| 10 | Ignoring a notice or e-mail | Ex parte orders and penalties follow | Respond on the portal within the time stated |
Worked example
A taxpayer earns a salary of ₹14 lakh and sells shares with short-term gain of ₹2 lakh, and earns bank interest of ₹40,000. Form 16 shows only the salary. AIS reports all three.
- If the return omits the gain and interest, taxable income is understated by ₹2,40,000.
- Section 143(1) processing may add the amount and demand tax with interest; if the omission is found later, section 270A penalty can apply at 50% of the tax on under-reported income (verify the rate and conditions).
- If the return reported all items and the taxpayer verified the return, the intimation would show no demand.
Which notice means what
| Notice or communication | Meaning | Typical response |
|---|---|---|
| Section 143(1) intimation | Result of automated processing; may propose an adjustment | Accept, or file a rectification request, or disagree on the portal within 30 days |
| Section 139(9) defect notice | Return is defective | Correct within the period given (15 days, extendable) |
| Section 142(1) notice | Inquiry before assessment | Reply with documents by the date given |
| Section 143(2) notice | Scrutiny selected | Appoint a representative and reply to the questionnaire |
| Section 148 and 148A | Reopening for escaped income | Respond to the 148A(b) notice; challenge limitation and jurisdiction where available |
Pre-filing checklist
- Download AIS, TIS and Form 26AS and compare with books.
- List all bank accounts, including inactive accounts.
- Collect capital gains statements from every broker and fund house.
- Check Schedule FA and the ESOP and foreign share position.
- Match deductions with documents.
- Choose the right regime (new or old) and the right form.
- Verify the return and keep the acknowledgement.
Frequently asked questions
What is the time limit to verify an ITR?
Can I file a belated return for FY 2025-26?
What if AIS shows income I never earned?
What happens if I forget a foreign bank account?
Can I correct a return after filing?
Does this apply to returns under the 2025 Act?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.