
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Will, gift or family settlement: pick the tool before the dispute picks for you.
A father in Hyderabad wants his two children to inherit a house and a plot without a fight. He can leave a will, give the property now by a gift deed, or record a family settlement. Each works differently in law and tax.
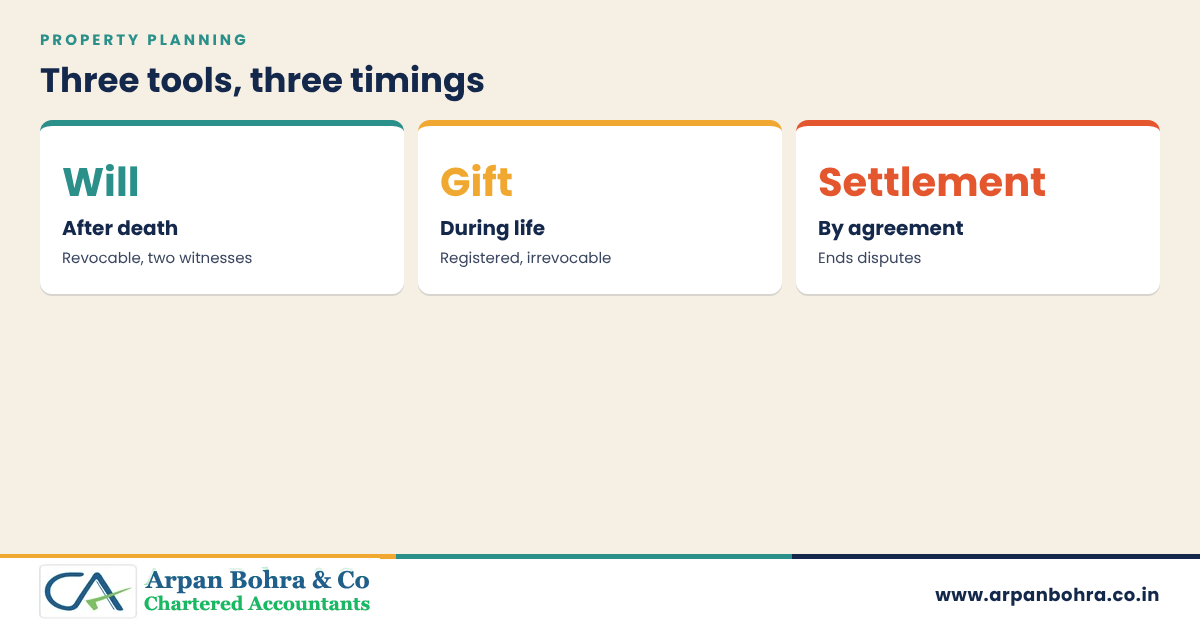
A will operates only after death, can be changed any time, and needs the testator’s signature and two attesting witnesses (section 63, Indian Succession Act, 1925); registration is optional. A gift deed transfers immovable property during life and must be a registered instrument signed by the donor and attested by two witnesses (sections 122 and 123, Transfer of Property Act, 1882). A family settlement resolves existing or likely family disputes by agreement and is treated favourably by courts. Gifts to specified relatives are not taxable to the recipient, and a gift is not a transfer for capital gains; stamp duty is a State matter.
Comparison
| Point | Will | Gift deed | Family settlement |
|---|---|---|---|
| When it takes effect | On death | On registration | On agreement |
| Revocable? | Yes, any time | No, once accepted and registered | Binding on parties |
| Formalities | Signed by testator, two witnesses | Written, signed by donor, attested by two witnesses and registered for immovable property | Written memorandum is advisable; registration is needed only if the document itself creates rights over immovable property |
| Probate | Not needed in Hyderabad as a rule; mandatory only in the former Presidency towns of Mumbai, Kolkata and Chennai for certain wills (verify) | Not applicable | Not applicable |
| Tax | No tax on inheritance | Not taxable to a relative; capital gains exemption on transfer by gift, with cost of the donor carried forward | No tax on partition among family; capital gains analysis needed for any consideration |
| Challenge risk | Capacity, undue influence and suspicious circumstances | Revocation only on limited grounds | Fraud or coercion; courts uphold family arrangements |
Making a will that survives
- The testator must be of sound mind and not a minor (section 59).
- Two witnesses must each see the testator sign and sign in his presence; a beneficiary should not be a witness.
- Describe each asset clearly with survey numbers and account details.
- Appoint an executor and consider registering the will and keeping a medical-fitness record near the date of the will.
- A Hindu may dispose of his own and, under section 30 of the Hindu Succession Act, 1956, his coparcenary share by will; daughters are coparceners by birth (Vineeta Sharma v. Rakesh Sharma, Supreme Court, 2020), so family property needs careful drafting.
Gift tax points
| Recipient | Treatment under the Income-tax Act, 1961 (verify the 2025 Act) |
|---|---|
| Relative as defined in the Act | Exempt, regardless of the amount |
| Non-relative | Taxable above ₹50,000 in a year as income from other sources |
| Any recipient, on marriage or inheritance | Exempt |
| Capital gains for donor | Gift is not a transfer under section 47(iii); the recipient takes the donor’s cost and holding period when he sells |
Stamp duty and registration charges on a gift deed are State-specific; verify the Telangana rates and the concession for family members.
Worked example
A father owns a house and a plot and has two children. He wants the house to go to his son now and the plot to his daughter on death.
- He executes a registered gift deed of the house to the son, paying stamp duty, with two witnesses.
- He executes a will for the plot to the daughter, with two witnesses and an executor, and registers it.
- The son’s later sale of the house is taxed on the father’s cost and holding period.
- A family settlement memorandum signed by all records the arrangement and reduces the risk of challenge.
Checklist
- List assets and family members and decide which assets go by will, gift or settlement.
- Verify title and encumbrances on each property.
- Draft the documents in plain, precise language.
- Complete execution formalities: signatures, witnesses and registration.
- Pay the State stamp duty and registration charges.
- Update nominations on bank accounts, mutual funds and insurance, which pass by nomination rules.
Frequently asked questions
Is a will valid without registration?
Is probate required in Hyderabad?
Is a gift to a relative taxable?
Can a gift deed be revoked?
Is a family settlement registered?
What passes by nomination and not by will?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.