
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Cancelled GST registration is not the end, if you act within the window.
A Hyderabad trader returns from a long trip to find that the GST officer has cancelled the registration for non-filing of returns. Customers cannot take credit, the e-way bill facility is blocked and returns cannot be filed. The law provides a revocation route, but the clock starts running on the date of the cancellation order, not the date the trader discovers it.
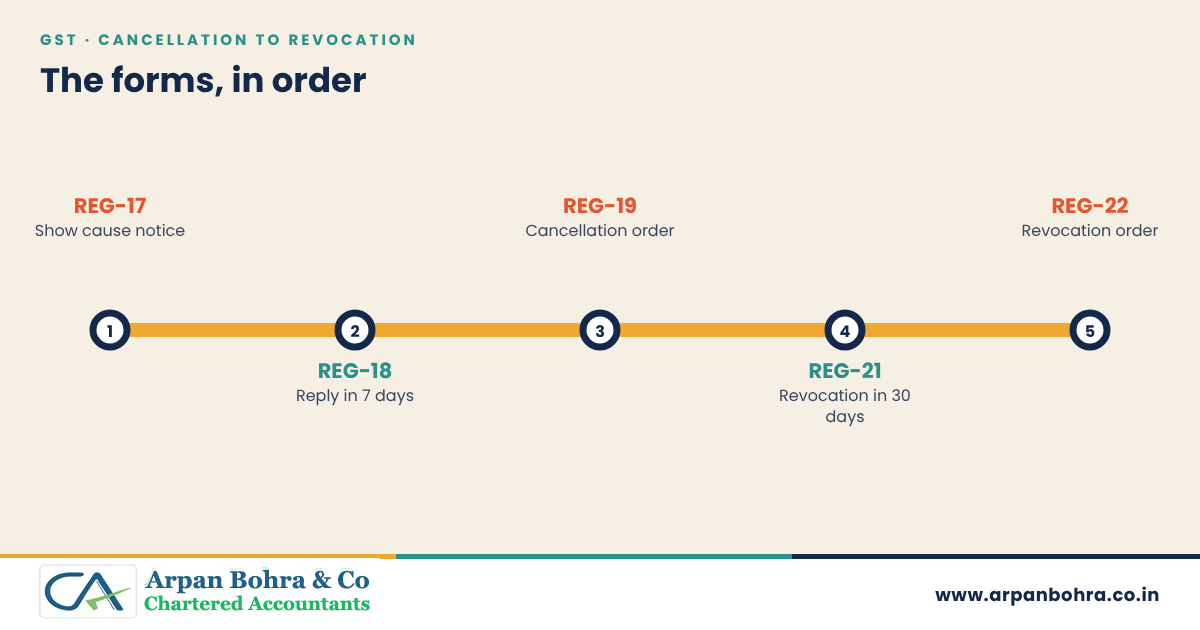
The proper officer may cancel a registration under section 29 and Rule 21 on grounds such as non-filing of returns for the prescribed period, not carrying on business, or fraud. A show cause notice in Form GST REG-17 must be issued under Rule 22, and the taxpayer may reply in Form GST REG-18 within seven working days. If the registration is cancelled, an application for revocation lies in Form GST REG-21 under section 30 and Rule 23 within 30 days of the order. The period can be extended in the cases and by the officers specified in section 30 (verify the current extension limits).
Grounds for cancellation
| Ground | Provision |
|---|---|
| Business closed, or no business at the declared place | Section 29(2)(a), Rule 21 |
| Not filing returns for six consecutive months (regular), or for a continuous period of two consecutive tax periods in the composition and QRMP cases as prescribed | Section 29(2)(c), (d), Rule 21 |
| Registration obtained by fraud, wilful misstatement or suppression | Section 29(2)(e) |
| Violation of the anti-profiteering and other specified provisions | Section 29(2)(b) |
| Taxpayer’s own application | Section 29(1)(a) |
Rule 21A allows suspension of registration pending the proceedings. The exact periods for non-filing differ by category; verify the current text of Rule 21.
Cancellation and revocation process
- SCN in REG-17 stating the grounds and the hearing date.
- Reply in REG-18 within seven working days, with documents.
- Order in REG-19 within 30 days of the reply, or a drop of proceedings in REG-20.
- Revocation application in REG-21 within 30 days of the cancellation order (extendable as the Act provides).
- Order in REG-22 within 30 days of the application, or a rejection notice in REG-23 with a reply in REG-24.
- Appeal to the appellate authority within three months of the rejection order under section 107.
Worked example
The cancellation order is dated 5 March 2026 for non-filing of returns for six months.
- Revocation application in REG-21 is due by 4 April 2026.
- Before applying, file all pending returns and pay the tax, interest and late fee due up to the date of cancellation. This is a precondition for revocation in such cases.
- If the application is filed on 20 May 2026, the delay beyond 30 days needs an extension under section 30 and the officer’s discretion.
The dates are illustrative. Count from the date of the order, not its receipt, and file early.
Litigation angle
- A cryptic or generic SCN that does not state the reasons is open to challenge, since Rule 22 requires the grounds to be stated.
- Cancellation with retrospective effect needs reasons and cannot ordinarily be made without them; challenge such orders where the revenue is not at risk.
- Where the limitation for revocation has expired, the High Courts have in some cases permitted late revocation by writ, often with conditions. Treat that as a discretionary and litigative route.
- Reversal of input tax credit on stock and capital goods under section 29(5) arises on cancellation. Plan for it.
Checklist
- Find the order date and the SCN on the portal.
- File all pending returns and pay the dues.
- Prepare a covering letter explaining the reasons for default.
- Apply in REG-21 on the portal with proof of filing.
- Track the REG-22 order and respond to any REG-23 notice in REG-24 on time.
Frequently asked questions
What is the time limit to apply for revocation of cancellation?
Is revocation available when I applied for cancellation myself?
Can I file returns after cancellation?
What happens to my input tax credit on cancellation?
Can I appeal if revocation is rejected?
Can I get a new registration instead?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.