
By CA Arpan Bohra (FCA, CS), Arpan Bohra & Co., Chartered Accountants, Hyderabad. Position of law as at 20 October 2026.
Interest, fee and penalty: know which one you are paying.
A business owner files the return two months late and discovers three charges on the computation: interest for late filing, interest for short advance tax and a fee. Interest compensates the Government; a fee is a flat charge; a penalty is imposed after proceedings. They have different triggers and different defences.
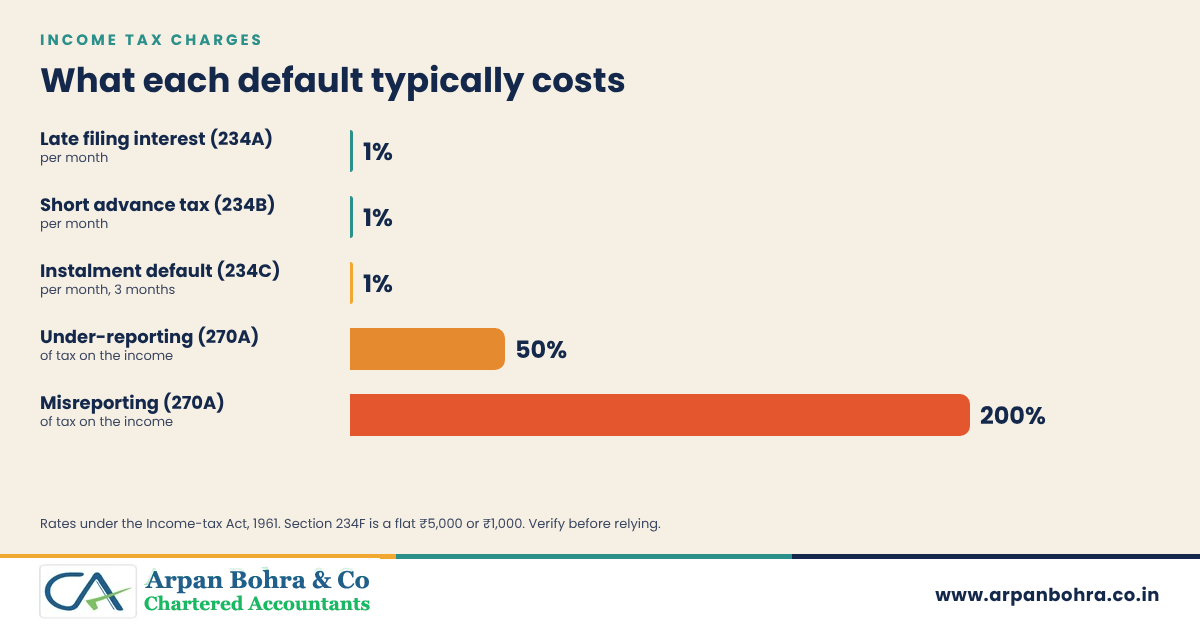
Interest under sections 234A (late filing), 234B (short advance tax) and 234C (deferred instalments) is mandatory and computed at 1% per month or part of a month. A fee under section 234F is ₹5,000 for a late return, or ₹1,000 where total income does not exceed ₹5 lakh. Penalty under section 270A is 50% of tax on under-reported income and 200% on misreported income, and is imposed only after an order. These sections are those of the Income-tax Act, 1961 for FY 2025-26; verify the corresponding sections of the 2025 Act for later years.
The charges at a glance
| Section | Trigger | Amount |
|---|---|---|
| 234A | Delay in filing the return | 1% per month or part of a month on the unpaid tax |
| 234B | Advance tax less than 90% of assessed tax | 1% per month or part of a month |
| 234C | Instalment of advance tax short or late | 1% per month for three months on the shortfall (one month for the final instalment) |
| 234F | Return filed after the due date | ₹5,000; ₹1,000 if total income is up to ₹5 lakh |
| 270A | Under-reporting or misreporting of income | 50% of tax on under-reported income; 200% for misreporting |
| 271B | Failure to get accounts audited | 0.5% of turnover or receipts, maximum ₹1,50,000 |
| 271H | Failure to file TDS statements correctly | ₹10,000 to ₹1,00,000 |
Interest, fee and penalty are different
- Interest is a statutory consequence, with no discretion to waive except under the Government’s settlement or reduction powers.
- Fee under section 234F is automatic and charged on filing.
- Penalty needs a show cause notice, an opportunity of hearing and an order, and can be appealed to the Commissioner (Appeals) and the Tribunal.
- Prosecution is separate and arises for wilful offences such as wilful evasion, subject to the Act.
Worked example
Tax payable after TDS is ₹2,00,000. The return is filed 2 months and 10 days after the due date; advance tax paid was nil.
- Section 234A: ₹2,00,000 × 1% × 3 months (part of a month counts as a month) = ₹6,000.
- Section 234B: ₹2,00,000 × 1% × months from 1 April of the assessment year to the date of payment, as computed on the portal.
- Section 234F: ₹5,000, because income exceeds ₹5 lakh.
The amounts are indicative. The portal computation controls, and interest is computed on the tax as reduced by credits.
Defending a 270A penalty
- The notice must specify whether under-reporting or misreporting is alleged; a notice that does not specify the limb is defective on the view of several High Courts (verify the current position).
- Show bona fide disclosure, complete material facts and a plausible legal view.
- Under section 270AA, immunity from penalty and prosecution is available if tax and interest are paid and no appeal is filed within the time allowed, and the application is made in time.
- Misreporting needs positive findings such as misrepresentation or suppression of facts, not mere disallowance.
How to reduce exposure
- Estimate advance tax each quarter and pay by 15 June, 15 September, 15 December and 15 March.
- File the return by the due date even if tax cannot be paid at once.
- Pay self-assessment tax before filing to stop interest.
- Disclose uncertain positions in the return with notes.
- Reply on time to notices and keep proof of the reply.
- Consider the section 270AA immunity application where eligible.
Frequently asked questions
What is the late fee for filing an ITR late?
Is interest under section 234A waivable?
What is the penalty for under-reporting of income?
When is the penalty for audit failure levied?
Can a penalty be imposed without a hearing?
Do the same rates apply under the 2025 Act?
Arpan Bohra & Co., Chartered Accountants, Himayat Nagar, Hyderabad.
This article is shared for general professional education. Readers may write to the firm for information about its practice areas.
General educational information as at 20 October 2026. It is not legal or tax advice and does not create a professional relationship. Provisions, rates and thresholds change; verify the current law and notifications before acting. References to the 57th GST Council (8 October 2026) are to recommendations that need amendments or notifications before they have legal effect.